
Downsizing

Downsizing

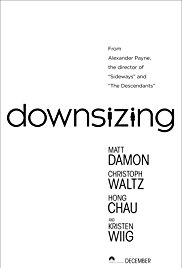
Imagine a world where your wealth is sufficient for the rest of your life to fully support your lifestyle. Throw in the benefit of massive improvements to the environment and waste reduction and you have the plot summary of Alexander Payne’s new movie “Downsizing”.

This is a movie that is tipped for the OSCARS, given that it will be released in December in the US and January 2018 over here in the UK. Whilst having potential for perhaps both comedy and a sense of hope, this is a film that gets loses itself in a story that is both too big and too small. It’s a pity as the premise is pretty good and the trailer is typically engaging
As a financial planner, my job is to help clients figure out how much is enough to support their lifestyle (as they determine it) for the remainder of their lives. Most people do not appear to have a financial plan, very few have a clear idea about how much would be enough.

Side Effects

Downsizing begins with the scientific discovery that means it is possible to shrink cells without harm or side effect to about 3% of their original size. The one problem being that it is an irreversible process and not available to anyone that has a body with additions (implants, prosthetics, pace-maker etc) as these will not shrink.

Living the Dream

Paul Safranek (Matt Damon) is your average American, he was once on the path to a career in medicine, but his dreams were thwarted by an ill mother who needed his care. Now a somewhat frustrated physiotherapist, he is living in his late mother’s home, with wife Audrey (Kristen Wiig) and struggling to get by. At the perfectly imperfect setting of a school reunion, he is persuaded to consider Downsizing, the solution to his financial struggles.

Paul and Audrey head off to Leisure Land and receive a masterful sales pitch that extols merely the benefits of Downsizing, ignoring all of the drawbacks. The Safranek’s have assets of $52,000 but in the Downsized world this translates to $12.5million, to live on for life! The numbers do all the talking. Packing a delightful red keepsake box with their family treasures (wedding rings etc) the same box is delivered to the house in Leisure Land, but of course gold wedding rings now appear the size of buoyancy rings. I have to admit, that if I could arrange such a return for our clients I’d be winning every award under the sun. However, as with all things, there are no guarantees.

The Bigger Picture

The plan to save the world is to gradually miniaturise everyone over the course of 200 years. Despite a safe procedure (assuming removal of fillings etc) there are very real side effects in the larger world – economic, political and social. Its all very well that a mansion may now only require the space of a dining table, but property in the larger world still needs to be sold and therefore bought. Taxes need to be paid, production needs to continue and there is a debate about whether the Lilliputians should have a full-sized vote.

The film attempts a stab at all these issues as well as a rather fruitless assessment of a life of pleasure, the poverty divide, immigration and those that remain outside the system, where standards are never the same. Add a touch of impending environmental disaster and the naive, blancmange-like character of Paul Safranek who seems to lack either any sense of self-determination or self-awareness, chasing every ball thrown by anyone willing to bother. Ironically, all of the issues are far too big for the film which becomes as microscopic as its characters, lost in a world of complexity. It’s a pity. Much like Safranek, it appears nobody asked what it was that Alexander Payne wanted from this. Instead it’s a journey of happenstance, rather than any course being plotted. I suppose that this is the reality for most people, who live from day to day, month to month, year to year without any deeper sense of direction, like Safranek, frustrated through not identifying purpose. Nobody asks the right questions and so the thinking is as shrunken as the inhabitants of Leisure Land.

Here’s the trailer, the film is released in the UK in January (following its showing at the London Film Festival this month). Oh yes, the trailer is the best bit.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Downsizing2025-02-03T10:37:22+00:00

Film Stars Don’t Die in Liverpool

Film Stars Don’t Die in Liverpool

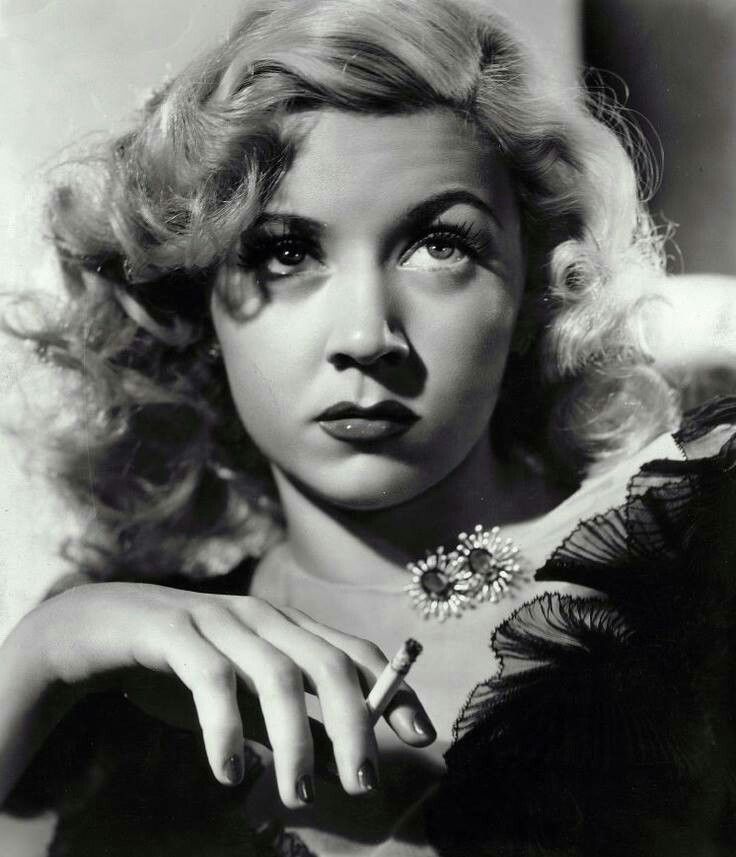
I have been enjoying several films at the BFI London Film Festival. One that stood out for me was “Film Stars Don’t Die in Liverpool” which is adapted from the book by Peter Turner. It tells of the unusual relationship between a young Peter Turner and former film noir femme fatale, who most are likely to have seen but perhaps not remember – Gloria Grahame.

Grahame’s career in film began with a small part in “It’s A Wonderful Life” you may recall how George Bailey gives Violet Bick funds to escape the small town and make a name for herself elsewhere. She won an OSCAR for her role on The Bad and the Beautiful and performed with some of the leading lights of the 1950s.

In A Lonely Place

The film is based on her encounter and 2-year relationship with Turner, who she initially meets in London whilst back treading the boards. Then in her mid-fifties, divorced 4 times and surrounded in scandal she begins a relationship with Turner, who at 27 wasn’t even born when Grahame had completed work on The Bad and the Beautiful. We are shown brief insights into her chaotic world and the scandals that inevitably ended her career in film. Her last husband, Anthony Ray, was her stepson (from her second husband) and the marriage lasted from 1960 until 1974 resulting in two children.

A Woman’s Secret

The film implies that Grahame was pretty much financially ruined, appearing to possess a mobile home / caravan on the Californian coastline. Perhaps because of 4 divorces or a career that was cut short, or even because of illness, but clearly the glamour and glitter of her star had burned out. (Spoiler) Ultimately her life is cut short due to a recurrence of cancer, though this is fairly evident as the likely outcome from the start of the film, so I’m not really spoiling it for you.

Odds Against Tomorrow

There are some broad financial lessons here. The audience laughter at a scene where two pints of beer are ordered for 90 pence, was probably the loudest in a film that clearly isn’t designed to be funny; but the long-term impact of inflation is not really the most obvious lesson here. Fame that brings financial success can be very short-lived. Life as an actor can be very harsh. Divorce is financially expensive, but of course the toll on emotional reserves may also be overwhelming. Love and tenderness are often found in unexpected places and whilst care costs, it may not have a monetary price. In a world of appearances many are in danger of making similar “mistakes” or having similar experiences.

The Cobweb

Financial protection is a modern-day (or should that be post-modern?) wonder for those without capital – providing financial stability in the event of life presenting “challenges”. Running out of money isn’t as bad as running out of time, but it’s probably a pretty close race. A proper financial plan will help reveal where your resources are and what you can do to sure them up. It enables you to take a look at the future and make some adjustments in advance if you don’t like the prospects.

Here’s the trailer for the movie, which reunites Jamie Bell and Julie Walters, this time as mother and son, whilst Annette Bening gives a great performance as Gloria Grahame.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Film Stars Don’t Die in Liverpool2025-02-03T10:37:22+00:00

The Trouble With…

The Trouble With…

It seems impossible not to feel a sense of despair sometimes when you see, read or hear the news. When there are atrocities on our own streets or we see yet further mindless violence in countries with whom we have deep and long connections, the sense of despair is palpable. However bad or inept the reporting, I remain thankful that I live here in the UK.

I’m not alone in thinking that the man currently elected as President of the United States is simply not fit for the task. He is out of his depth and displays his evident lack on a daily basis. We have come, (well…I have) to expect very little from him.

Viva Espana?

Spain on the other hand, is a country that most of us know almost as well and the US. Our language barrier is possibly helpful as we tend not to make too many assumptions about each other. Yet I am struggling to understand what goes through the mind of a policeman in the Spanish Civil Guard who appears to enjoy stamping, beating and fighting anyone he deems to be “opposition”. The images that have crossed a multitude of screens are truly horrifying. Whilst the vote for independence may be “illegal” it is clear that a very significant proportion of those living in Catalonia do not wish to remain part of Spain.

Splitting Heirs

As an Englishman and a British citizen, I’m aware of the calls for devolution of power and potential independence of Scotland, Wales, Northern Ireland and perhaps Cornwall. This is unsettling to my sense of what is “normal” but of course the history of our own union is relatively recent and things were different before, much as they were in Spain, Italy, Germany, France, Prussia and so on… borders change. We do not keep the peace by pretending that all is well. We do so by listening to the perspective of the other. As in a marriage that reaches the point of irreconcilable differences, we need to acknowledge that sadly (perhaps) the best course of action is to separate and ultimately to agree to the new legal state of all parties concerned. This will have some genuine difficulties, just like a divorce, the division of resources and accounting for what belongs to who is painful. Those of you that have been through a divorce will understand this more pertinently than those that have not.

Head of State or State of Mind?

The suggestion that “the law” is to be upheld as though it is never altered based upon real experience is nonsense. The law is formed from experience and always evolves to reflect the changing nature of society. When a Monarch, President or Prime Minister fails to grasp the sense of unfairness felt by “their own people” preferring to support aggressive legitimised bullies, it seems to me only right to call them to account.

Ceteris Paribus

What has this to do with financial planning? We make assumptions about the future all the time. The biggest ones are those we don’t even verbalise – such as a relationship lasting. At my annual Institute’s Conference, last week, I expressed this view and to be honest, it didn’t seem to “land” with the small group that I was with. We talk of risk – typically investment risk, but also political and economic risk, occasionally the risk of health or redundancy, but rarely the risk of relationships ending. It is the elephant in the room with all couples, do we talk about the risk of irreconcilable differences?

I’m reminded of the saying “the pessimist complains about the wind, the optimist expects it to change, the realist adjusts the sails“.

Feedback welcome, but not for a debate on the issues of Scottish Independence or devolution, or even what’s going on “abroad”. We can only control a very small number of things, but our ability to face up to our assumptions is one of them. For the record, I “love” Britain, Spain, the US but I prefer human dignity over any flag.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
The Trouble With…2025-02-03T10:37:23+00:00

Cold Feet

Cold Feet

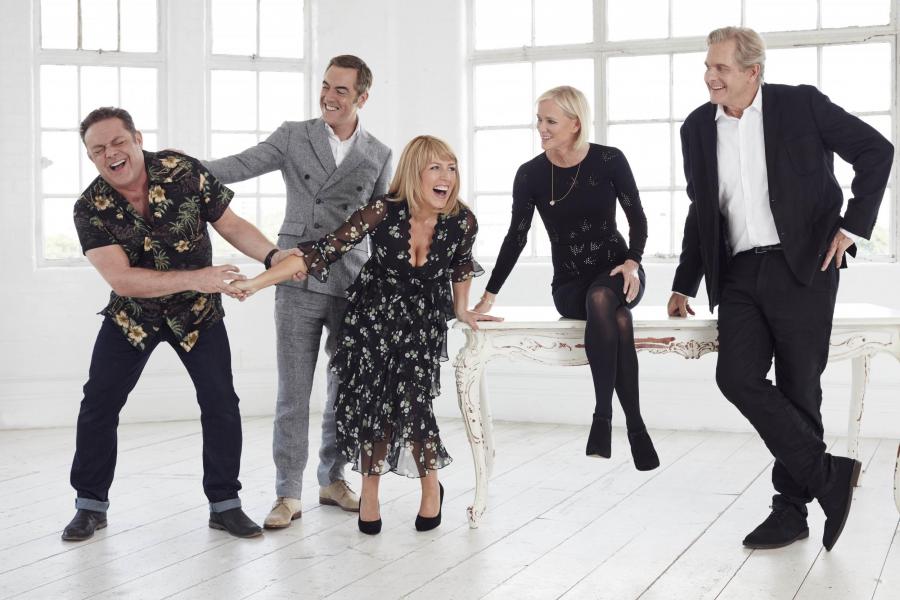
Perhaps you have been watching the new series of Cold Feet. The original series began in 1997 – some 20 years ago and ran until 2003. It was revived last year. Originally a series about three thirtysomething couples living in Manchester, we have seen the usual plethora of “dramatic” storylines. Any significant exploration of characters or plot reveals a number of gaping holes and sadly even in the decade or so of a break, the writers have continued to fail to redeem themselves.

The Hapless David

David Marsden, the character played by Robert Bathurst has had to contend with a fair amount of turmoil in his life. Now, two marriages, various affairs and of no fixed abode later, his already somewhat questionable career (from anything believable) has now developed into that of Independent Financial Adviser.

Financial Planning for the Filthy Rich

In the latest series (7) we have seen Mr Marsden provide a presentation to a collection Manchester’s wealthy women, held in the plush executive home of Nikki Kirkbright, with Champagne freely flowing and perhaps more like an Anne Summers party, he proceeds to rename his “talk” financial planning for the filthy rich.  David meets with Nikki who clearly wishes to keep the matter from her husband who returns home and results in David being asked to leave quickly to avoid meeting him. The latest episode had David meeting discreetly with Nikki, a meeting which he claims he has all the forms for the Unit Trusts. Her husband finds out and has David collected for a “meeting”.

David wouldn’t be an “Approved Person”

I don’t really know where to begin with this, save that David would not be a financial adviser having been arrested, charged and imprisoned for fraud – for his arrangement of what can only be unregulated investments whilst working for a firm that clearly are equally as inept at understanding financial regulation. His firm leaves him to “hang out to dry” and of course David attempts to pass the buck and record his boss admitting liability. His only obvious punishment is that at the start of series 7 he is to be found visiting very elderly ladies and encouraging them to sign application forms to release equity from their home or buy life assurance.

David Marsden is without shame, without qualification and frankly without any credibility. Someone in the writing team must have had a rather bad experience, but has clearly allowed that experience to dictate terms that no further understanding of finance shall be permitted. David is utterly incompetent, totally untrustworthy and completely delusional.

Trust Me, I’m A….

Of course, misrepresentation on television is nothing new, (ask Doctors, Lawyers, Nurses, Teachers, Ministers, Police and anyone in the Armed forces) and yes, it’s just light-weight comedy-drama, designed to amuse, not inform. Fair enough. I’m more concerned at the continued lack of understanding of finance and whilst yes, these characters aren’t real, they really don’t help anyone improve their own understanding of financial services, but merely compound the problems with misinformation. Dont get me wrong, I quite enjoy the series, I simply wish that there was rather more credibility in the characters…. you can watch it here:

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Cold Feet2025-02-03T10:37:23+00:00

Another Concerning Survey

Another Concerning Survey

If you have followed me for any reasonable time, you will have gathered that I am fairly suspicious about surveys and opinion polls, primarily due to the very small sample sizes and the eagerness to extrapolate data from, well, frankly not very much.

That said, yet another survey has revealed more of the problems that, if correct, are concerning for the country. Paymentsense (a card payment service) clearly have an insight into how people spend money. They surveyed 1000 people last month (July 2017) of all ages, whether this is a truly representative sample… well, it won’t be. However, the findings are certainly of concern.

30% of UK Have No Savings

Firstly 30% have no savings at all for a “rainy day”. Of those that had savings 21% used them for a holiday and only 17% put savings towards their retirement. Here is where I also have an issue with the line of questioning (which is unclear from what I have seen) but this could have been interpreted as using cash deposits to add to a pension (into which they may already be saving). Some people may of course be already retired and have no purpose in “saving for retirement”. In any event, a pension would be what springs to mind when asked about saving for retirement, but of course there are a huge number of ways to invest into something which will ultimately provide an income and/or capital.

Nothing in reserve?

However, the headline grabbing figure is really the extrapolation of the data. This leads to the conclusion that some 45.5m people have less than one month’s salary set aside in “savings”. The population is now an estimated 65.6m, which obviously includes children, pensioners and anyone simply unable to work and “earn” income. The current “unemployment” rate is 4.4% (for 16-64 year-olds). In short, a significant economic blip would be likely to cause significant hardship for a lot of people if they lost their income for whatever reason.

Signs of uncertainty shown in house sales

As Government continue with plans to leave the EU and a growing awareness of the likely implications for UK jobs, it would appear logical to be concerned. Hence the property market isn’t exactly booming, but property prices do continue to rise (4.9% over 12 months to June 2017) according to the Land Registry, however the number of sales continues to fall from 98,152 in August 2016 to 69,545 in April 2017. As a matter of note, the lowest number of house sales was in 32,752 in January 2009. The highest was June 2006 with 153,465 (for all the UK). If it is of interest, over the last 20 years, the average property in the UK was £65,092 in August 1997 and now stands at £223,257 (June 2017).

If you like short animated films, then Borrowed Time is a delightful one and a powerful message. Here is the trailer (almost as long as the film).

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Another Concerning Survey2023-12-01T12:18:26+00:00

The Value of Financial Advice

The Value of Financial Advice

There is a new report by the International Longevity Centre (yes another that nobody has heard of) about the value of financial advice. Long story short, the research asked a wide range of people, over 91,000 households were surveyed (for the record, according to ONS there are about 27.1m households in 2016 of which 7.7m are one-person households). So it’s a far better survey than any of the cosmetic adverts you might see on TV, where number is invariably in the low 3-digits if you can read their faint printed disclosure). So this is a survey that I have a little more confidence in.

The headline is that anyone that took financial advice from someone qualified to provide it, was about £40,000 better off than those that didn’t when they had comparable wealth and socio-economic backgrounds. This was over 2012-2014. In essence, the report concluded that those that were advised were better savers and invested in assets that would or did grow. However only 16% of the general population take advice.

Affluent or Justing Getting By?

There were two key groups – “affluent” and “just getting by”. The affluent group generally had 17% more wealth due to being advised and the “just getting by” advised group had 39% more in liquid wealth and 21% more in pensions.

Ker-ching…Cash Machine

In short, (too late) getting advice will improve your wealth, in the timeframe considered, this was by an average of around £40,000 improvement in the period concerned. Whilst this is obviously helpful news to anyone considering financial advice, frankly I would expect a financial planner to add significantly more value than this (a multiple of £40,000). Some of which is measurable (financially) some is not (peace of mind, freedom from debt, retiring early, knowing your number). In fact if done properly, then a financial planner would expect to improve the value of the estate and retained value (post inheritance taxes). They would ensure a sufficient lifetime income – so that the money does not run out and minimise taxes, maximise reliefs. At Solomons we would also expect to improve investment and protection costs as well.

The Report Concludes

Directly quoting the report:

“Advisers must sell their added value: This report demonstrates the real value add of financial
advice – in terms of greater asset accumulation during working life and increased income in
retirement. Since those who receive advice accumulate more assets and have more retirement
income than those who don’t, this shows that advisers are good value for money. Post RDR,
people now understand what taking advice will initially cost them, but many of those who fail to
take advice are unlikely to know what the potential long term financial rewards are. It is up to the
advice sector to convince them.”

The Value of financial advice, A Research Report from ILC-UK July 2017

Cesira Urzi Brancanti, Ben Franklin and Brian Beach

So… what are you waiting for?

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
The Value of Financial Advice2025-02-03T10:37:23+00:00

Hard Truths

Hard truths

As Wimbledon begins, some hard truths will be faced. Some players will not be “on their game”; some will peak too early and some will enjoy good luck whilst others might curse technology, training, lack of sleep or why on earth they did or didn’t do something that may have made all the difference. We will all have our favourites, but in the end only one person can win the singles championship. In just a couple of weeks all the questions, hopes and dreams for Wimbledon 2017 will be consigned to history.

In a similar vein, June was interesting and is now over. An election, a minority Government, a deal with the DUP, various horrendous disasters and circling political vultures all attempting to appeal to the crowds, some more obviously than others. Much of this we cannot control, despite what some might suggest within social media.

A new savings low

The FT reported the rather grim news that Britons are saving less of their disposable incomes that at any time since 1963 when such records began. An alarming 1.7% of income was left unspent in the first quarter of 2017, significantly below the long-term average of 9.2%. Reports also continue to make the argument that around 1 in 6 people use a credit card to get through the month. In tennis terms – there’s not enough left in the locker.

Squeezed rises

Whatever your view of austerity, clearly if income falls behind the rate of inflation, you effectively have a pay cut. This is something that the State Pension triple lock is designed to prevent (after many years when the State Pension arguably fell in real terms). It is estimated that the triple lock costs around £6bn. It would certainly appear that the days of austerity are coming to an end and that there is growing support for the end to the cap on Public Sector salaries which have been held back since 2010 (when Rafael Nadal won the men’s singles and Serena Williams won the women’s singles at Wimbledon).

Self-defeating

However, unless people begin to save for their own futures, arguments about austerity are going to seem like the proverbial storm in a teacup.  The undeniable truth is that we all need to budget and live within our means. Most don’t appear to do this. No Government in recent history has achieved it either. If you cannot control what you earn, you can only control what you spend, which means accounting for how your money is spent. The truth is that hardly anyone likes to budget and probably dislikes drawing one up a little more. Our clients are no exception – and most don’t really “need to budget” but of course it is a discipline that we advise and encourage to ensure that your hard-earned income sticks to you.

However, it is vital to understand where your money goes. The chequebook (remember those?) does not lie. It is very easy to spend and keep spending in a society that is expert in parting you from your hard-earned cash.

As with politics, in tennis with patience, generally your opponent will tend to beat themselves. Sure, you may need to play well, but invariably the loser is the one that makes the most and more significant mistakes or errors. The most basic of these to make in financial planning is failing to budget, ignore it at your peril. In tennis terms, its the equivalent of not being able to serve.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Hard Truths2025-02-03T10:37:24+00:00

A Case of Cops and Robbers?

A Case of Cops and Robbers?

There is an undeniable strange fascination with a story about bank robbery. Butch Cassidy and the Sundance Kid, The Great Train Robbery, The Italian Job, Bank Job, The Lavender Hill Mob, to name just a few. Perhaps there is something played out in the story that we might wish we could do, yet clearly do not. Perhaps the daring, cunning or planned deception appeals. Perhaps we admire something about “sticking it to the man” which in this instance is the large, faceless, corporate Banks, who we might tend to believe are the real robbers (anyone think their bank charges are fair?). This is of course nothing but escapism, a reality that thankfully we do not have to live with personally.

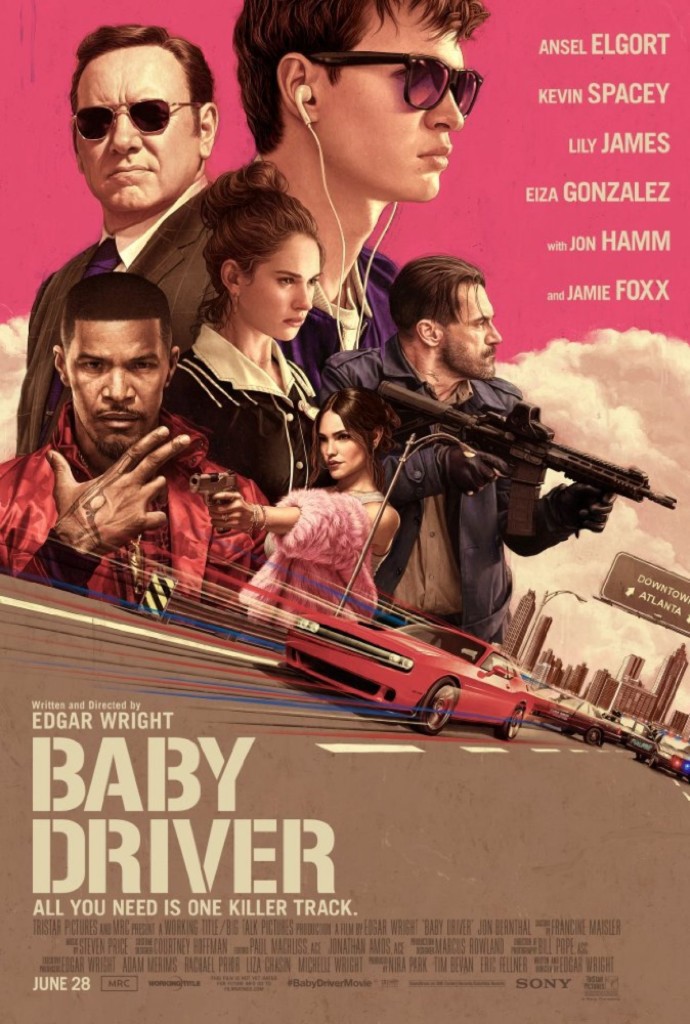
The new movie Baby Driver is on many levels another heist movie, a car chase, a gang and the inevitable show-down. Throw in a small romance and the ingredients are set another summer blockbuster. However, with the British Director Edgar Wright at the helm, who made comedy such as “Hot Fuzz”, “Shaun of the Dead” and there is arguably a more subtle nuance to the plot.

A Virtual Reality

In the days of computer games like Grand Theft Auto where players can commit all manner of crimes in the “safety” of a game without consequence, there are many that might ask questions about the impact on the player. Baby Driver attempts to draw from this conversation and whilst the first heist is very much like a clean version of a game of no consequence, each subsequent event gathers the reality of pain, suffering and ultimately the reality of loss. That said, I’m not too convinced that guns and violence are still not stylized and glorified within the film, there is still not enough consequence, but perhaps I am a little numb to violence within films.

Are you Being Served?

Consequences are of course something of a hot topic. Whatever your political views, the devastating fire at Grenfell Tower has triggered some significant discussion about the consequences of a divided society, divided on the grounds of have and have not. We have heard allegations about money being the motivation for almost every shortcut. Indeed the £1bn deal that Mrs May has struck with the DUP to many is an act of bribery and of course many now make the case that austerity has not worked and must cease, a policy that was the consequence of the financial collapse and the subsequent propping up of the system, which largely went to the balance sheets of the very Banks that created and manipulated the chaos. So we are back to robbing banks because of the belief that the banks are the bigger villains.

Bank Robbers…

The UK regulator (the FCA) has today issued a paper on how they would like to reform the investment banking community (like those that you probably see on billboards or sponsored events). Many have very high charges, most of which appear to be somewhat difficult to justify based upon performance. Indeed advisers such as myself that use evidence based investing as the basis for wealth management, combined with low cost techniques, have been calling for reform for quite some time. However, there is also the issue of extra charges and the regulator would like to see one all-inclusive charge. I don’t have a problem with the sentiment, however invariably complex problems are rarely easily solved with a simple answer. There always needs to be a context. None of us would actually rob a bank, let alone approve of it, our motivations for watching and loving such stories are clearly more complex.

The Good, The Bad and The Ugly?

Life would be pretty easy if the lines of “good” and “bad” were so easy to define, arguably the biggest flaw of all religions. Most Politicians seem yet to learn that most ideology is bereft of complex thought for the reality of life. The polarization of opinion is decidedly unhelpful. There are no magic money trees, but there are obviously ways to create money and to grow it. Taxing the rich is all well and good if you don’t drive them away. Keeping the poor in miserable conditions, where they feel powerless, unrepresented and ignored will eventually lead to inevitable calls to take power. Squeezing the middle classes until they feel bled dry whilst we celebrate and reward psychopathic bullies, be they CEOs or Heads of State (or party) isn’t going to help to establish a sense of fairness either. We live in complex times (as we always have). There are very few easy solutions to our complex problems.

Escape to the…

We in turn, escape to the sun, the country, the movies, our mobile devices and use stories to tell ourselves that good will triumph, that injustice will be exposed and punished. There is presumably a place between Utopia and Dystopia that most of us manage to call home, where we really live our lives that are full of complexity and a healthy degree of compromise.

A New Reality

As the Brexit negotiations are under way, we are certainly going to need to compromise. Posturing the EU as pure evil or pure heaven, will not help our understanding of the complex. I expect nothing other than unhelpful reporting from most of the media and social media, yet we must sift through it to garner the occasional nugget of wisdom. To pretend that feelings will not be hurt or damaged seems somewhat naïve, indeed even Bats, a character from Baby Driver says:

The moment you catch feelings is the moment you catch a bullet.

Anyway, here is the trailer.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
A Case of Cops and Robbers?2025-02-03T10:37:24+00:00

Be Careful What You Wish For..

Be Careful What You Wish For…

I wonder if you have ever thought about how you would live life if you won the lottery. Probably most of us have given this a moment’s thought at some point. Our society seems to hang on the belief that money makes everything better. The Financial services industry be unrecognisable if there wasn’t an underlying message that money is the answer to pretty much every question. Of course, money can make life better and we certainly need it. As you will often hear me say, money provides choices.

Trust No.1

Enter Dave Dawes who won £101 million with the Euro Millions draw in 2011. A truly life altering amount of money that most of us will never experience – thankfully. Anyone suddenly gaining “wealth” is always going to struggle with the consequences, the most fundamental being – a suspicion of pretty much everyone. So, it follows that the worst thing you can do is agree to a press conference about your newfound fortune, which is of course what the lottery organiser wants a winner to do.

Forget Fair

Most people have money struggles, not necessarily lacking money, but most have some “baggage” and everyone has an opinion. It is obvious that life is not fair and money is merely one example of it. Yet increasingly there is a belief of entitlement. Anyone with a modicum of common sense understand that wealth is invariably not earned and never earned single-handedly. The best entrepreneurs freely acknowledge the help of others. Inherited wealth is not earned by the recipient. The entrepreneur may well be some sort of genius, but it’s also partly luck – with their genes, health, education, family, connections, geography, ethnicity and so on – sure, probably worked hard… but acknowledge the good fortune as well. It ought to be plainly obvious that being rich has nothing to do with being a “nice” or “good” person and frankly it doesn’t have anything to do with how hard you “work”. It is virtually irrelevant.

Hero or Villain?

Clearly we have some cultural confusion about money as well. Robin Hood, Dick Turpin, The Great Bank Robbery…. all thieves, yet for many are held in high regard as bringing about some sort of fairness by taking from “the rich”. As we enter the general election wars of empy words, expect more of the same. A more interesting point of view about our love of pirates is shared by Kester Brewin in his book “Mutiny” which is worth a read.

When someone wins money, various “journalists” will do their very best to work a story one of two ways – either the person is really “nice” and “deserves” it, or isn’t and doesn’t. I get the sense that Mr Dawes has experienced life in the media as the latter – and of course we simply do not know the truth. The revelation that Mr Dawes’ adult son Michael felt that his father should give him rather more after he spent all of the £1.6m already given to him, resulted in a court becoming involved. Michael clearly had expectations about his inheritance or support due to his father’s wealth. He quit his job and (it is reported) enjoyed a lifestyle costing around £25,000 a month. Mr Dawes felt that his son had received quite enough. The judge in the case recently ruled against Michael who had been pressing for lifetime financial support. The relationships are evidently in tatters. It turns out that Dave Dawes actually gave away a lot of money to family and friends, but the amount was quickly overlooked by the proportion in the case of his son. I wonder how differently things may have been if he had “only” won a million?

Yet, whilst this is news (the court ruling was yesterday). It is about as old a tale as there is. The prodigal son springs to mind, at least with some similarities. Money, for all the good it can do, can also create tremendous damage. As the numbers get larger, the walls tend to get higher. Money is not evil, but its lack or abundance can certainly create the appearance of it.

A financial planning conversation is designed to reveal what you really want from life. Money is part of the conversation, but this is an opportunity for you to reflect on your values and what is genuinely important to you – whether you have a lot or a little. Importantly, we will help ensure that you do not live beyond your means, there is not a limitless supply. Only your imagination is limitless.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Be Careful What You Wish For..2023-12-01T12:18:32+00:00

Guardians of the Galaxy Volume 2

Guardians of the Galaxy Volume 2

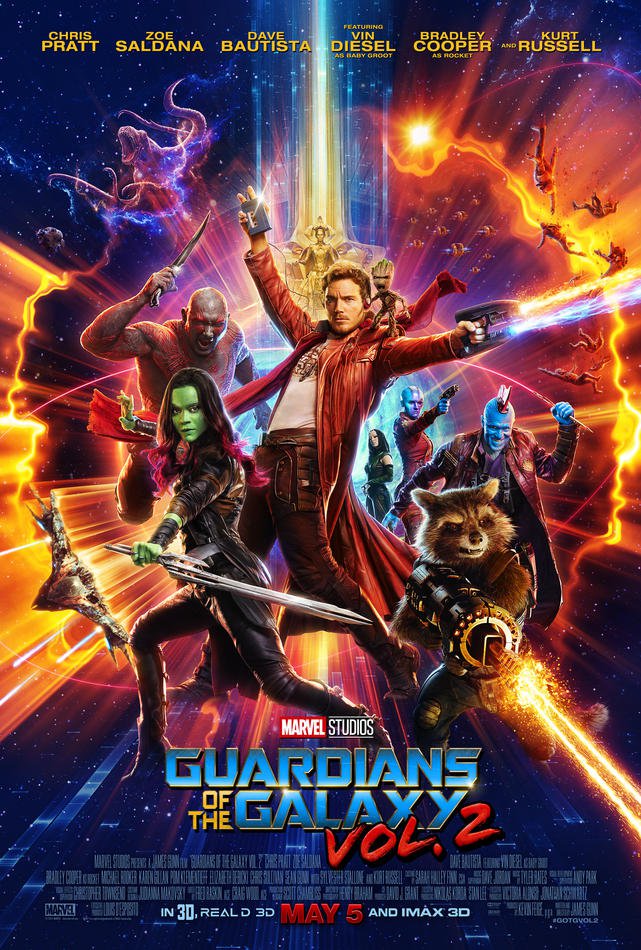
The myth, fantasy or religion of the superhero or saviour is pretty much embedded in every culture in the world. For those of us that grew up watching Spock, Kirk and Bones boldly go where no man had gone before, the idea of a mixed crew facing new existential threats in new frontiers is nothing new. The global melting pot that is post-modern America, is represented in contemporary superhero saviours.

Guardians of the Galaxy is one of the many branches of Marvel comic superheroes. Unlike many of the more two-dimensional superheroes that are “good” and fight “bad”, the Guardians are a more eclectic mix of pirates with a conscience, out to save life-kind. Any reading of most myths would likely suggest that subtlety is an unlikely prerequisite for the role of hero, saviour or guardian and this motley crew are as subtle as the obligatory movie soundtrack sale (ker-ching!).

Sadly, Guardians of the Galaxy Volume 2 is a rather more obvious copy of previous attempts of the same story, almost a direct copy of “Return to the Forbidden Planet” which is derived from “The Tempest” by Shakespeare. The CGI is obviously better, but essentially, it’s the same.

Superhero your financial plan?

So what on earth can a financial planner gain from a Superhero film? Well, perhaps a reminder that relationship is at the heart of everything and those that are obsessed with their own ego, the narcissists, are just about the worst people to hang out with. However, perhaps allowing for the more nuanced subtlety that real people (and real clients) require, there is one particularly vital lesson for investors. It is this. The perfect world does not exist…. life is brief.

The real world is as complex and as messy as the people that inhabit it. Investors seeking illusory risk-free bumper returns, yet despite regulation, your inbox or “newspaper” is probably crammed with offers of them. Investing in property because you believe equities are “risky” is a misunderstanding of both. We might want jargon free, easy to understand financial products (most could be substantially improved) yet we live in an imperfect world where often all is not as it appears and our own desires may not necessarily be the best path for us to take. Simple is not always better.

The Perfect Life?… good luck with that

We live in a world of fairly immediate gratification, yet there are consequences to every decision. What we require, all of us, is wise and good counsel, that is designed for our best interest, not necessarily the convenience of “perfection”, which is invariably disguised as more earthy, pithy virtues such as redemption or restoration of broken relationships… or perhaps simply finally attaining the approval of a parental figure, through the acquisition of “stuff” that is the equivalent of those unnoticed (or noticed) gold stars.

Our revels now are ended. These our actors,
As I foretold you, were all spirits and
Are melted into air, into thin air;
And, like the baseless fabric of this vision,
The cloud-capp’d towers, the gorgeous palaces,
The solemn temples, the great globe itself,
Yea, all which it inherit, shall dissolve,
And, like this insubstantial pageant faded,
Leave not a rack behind. We are such stuff 
As dreams are made on: and our little life 
Is rounded with a sleep.

The Tempest, Prospero Act 4, Scene 1.

As for Guardians, well it’s a bit of fun and in a world where distraction from the trials of life is the invisible drug that keeps most of us going, it will doubtless make a fortune. I hear that the third film is already commissioned. Here is the trailer for the latest movie, Guardians of the Galaxy Volume 2… and no it isn’t everyone’s cup of tea, however Guardians is all about the ordinary doing the extraordinary when sharing a common cause together as a family, tribe or group of misfits.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

Guardians of the Galaxy Volume 22023-12-01T12:18:34+00:00
Go to Top