CHRISTMAS BUDGETING

TODAY’S BLOG

SO, WHAT WAS YOUR BUDGET FOR CHRISTMAS? DID YOU EVEN HAVE ONE? AND HAVE YOU KEPT TO IT?…

I have to confess … I’ve gone over mine ever so slightly. I always forget how expensive the ‘treat foods’ are … not just the turkey and all the trimmings, but the nibbles you tend to leave dotted around the place in the run up to the big day; the spare bottle of bubbly (just in case); the oversized tin of Quality Street – that seems to be devoid of toffee pennies within minutes of opening (I always feel a bit sorry for the strawberry creams that get thrown away in the New Year when I’m sick of the sight of the tin loitering on the kitchen worktop!); don’t even get me started on Turkish Delight (about which I find not one delightful thing!)

This year I congratulated myself for managing to stay within my budget for ‘gifts’, but then I chastised myself because I failed miserably (as every other year) to budget for wrapping paper, ribbons, tags, tape etc.  (Anyone who has ever received a gift from me will tell you that I take the presentation of gifts quite seriously, so this is a rookie oversight on my part!)

What does all this boil down to in the context of what we do at Solomon’s? Simple answer … contingency planning (you knew the P-word was coming surely?!).

It’s about knowing that you are never going to remember every little cost. And planning accordingly. Giving yourself wiggle room. It’s something that every builder on the planet will tell you to do. Every project manager. Every business executive. We all KNOW this. But knowing what is good for us is the easy part. It’s the following through on that knowledge that is the tricky bit!
When we talk about ‘budgeting’ in general here at Solomon’s – we are encouraging our clients to be realistic and to err on the side of ‘over-estimating costs’ … thereby giving that wiggle room to the numbers.

We recently had some new clients who put together a really detailed and carefully considered analysis of their ‘normal’ spending. The numbers revealed that they potentially have a considerable sum ‘left over’ each month. When we presented this to them, they were stunned as this was not a fair reflection of their lived experience. So they had to look again and see where they were spending and not accounting for things. It was a revelatory experience … for them and for us!  It was a really good reminder that this is an incredibly difficult but vital component of the financial planning process.

If you haven’t updated your expenditure figures for us recently – we would encourage you to be brave and have a go at this in 2022 (but maybe don’t use your December transactions as a reflection of your ‘normal monthly spending’!!)

If you need a template to work from – please click here or you can have a go at using our portal to record your numbers. Or you can just let us have your own budget/bank statements and we’ll do the legwork for you.

However you choose to do it; please just have a go. After all – it is the foundation stone of the framework that is your financial plan and it’s vital that we place it in the correct position for you, so that it can bear the weight of whatever needs to go on top.

Debbie Harris
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

CHRISTMAS BUDGETING2023-12-01T12:12:58+00:00

A VERY BRITISH SCANDAL

TODAY’S BLOG

A VERY BRITISH SCANDAL

There is no Downton Abbey Christmas special, but if you enjoy a period drama vaguely based on events then Boxing Day offers up A Very British Scandal. Obviously, I have not seen the production, it has some top-drawer stars and is likely to be a hit for the BBC. So what has a period drama got to do with your financial planning? Well, it’s a story that has some useful messages. If I were a betting man (I’m not) I imagine that the focus will be on sex and power with a nod to things that have changed and some that have not.

I’m curious to learn if we ever witness the end of the story, or more accurately the end of Margaret Campbell, Duchess of Argyll who died in 1993 at the age of 80 and buried not many miles away in Brookwood Cemetery, Surrey. She would have been 109 this month!

Foy & Bettany - BBC A Very British Scandal

HIGH SOCIETY SCANDALS

However the story is retold by Sarah Phelps, it would be fair to say that the Duchess was a very wealthy individual, one whose life was full of high society life and celebrity. She was born to Scottish millionaire George Wigham who was Chairman of Celanese Corporation, still listed on the NYSE and possibly held in your portfolio (a tiny fraction). Her first marriage at the age of twenty was to American Investment Banker Charles Sweeny (23) whose family had a home locally in Wimbledon. Sweeny later went on to form the Eagle Squadrons of American pilots volunteering to fight in the RAF. It is alleged that the wedding dress designed by Streatham born Norman Hartnell caused such a stir in Knightsbridge that the traffic of the day was gridlocked for 3 hours. The couple divorced in 1947.

Her second and last marriage in 1951, aged 38 was to twice divorced Ian Douglas Campbell, the 10th Duke of Argyll and 9 years her senior (casting improved its actor age gap to 13 years).  Suspicious of her infidelity the story unfolds in a scandalous divorce in 1963.

It will be interesting to see how the story is retold given its previous framing by men in power, many of whom it is alleged knew the Duchess very intimately. A decade or so later her memoirs “Forget Not” were published. Quite what happened thereafter is significant as the Duchess mismanaged her investments and finances (or someone did) and in 1978 at the age of 65 she had to sell her Mayfair home and elected to move into a suite at the Grosvenor House Suites. Unable to pay her bills, aged 78 she was evicted in 1990.

PENURY – CASHFLOW EXHAUSTED

Whatever one’s view of the Duchess and the blatant hypocrisy of various powerful men, there are obvious lessons about choices and financial management that need to be remembered. Appearance is often not reality. How people say they live and how they actually live are often rather different. This is a familiar story, as old as storytelling itself. Your financial plan needs to be robust enough for changes in your circumstances, but a great financial plan has considered and will continue to address the issue of an affordable lifestyle.

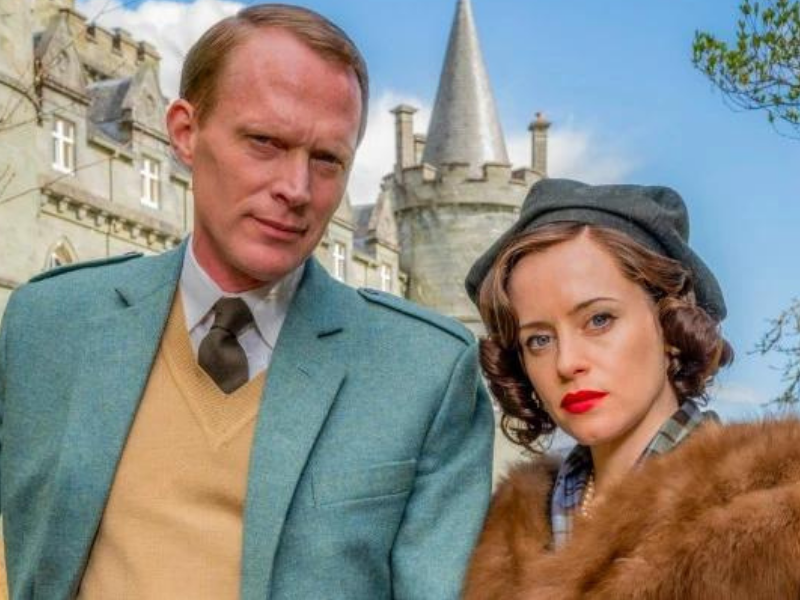
Claire Foy and Paul Bettany star in the BBC’s “A Very British Scandal” a 3-part drama starting on Boxing Day 2021 at 9pm. It will be shown on consecutive nights, but all three as a “box set” are also available via the BBC i-player from 9pm on Boxing Day. Here is the official BBC trailer.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?


GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

A VERY BRITISH SCANDAL2023-12-01T12:12:58+00:00

NOWHERE SPECIAL

TODAY’S BLOG

NOWHERE SPECIAL

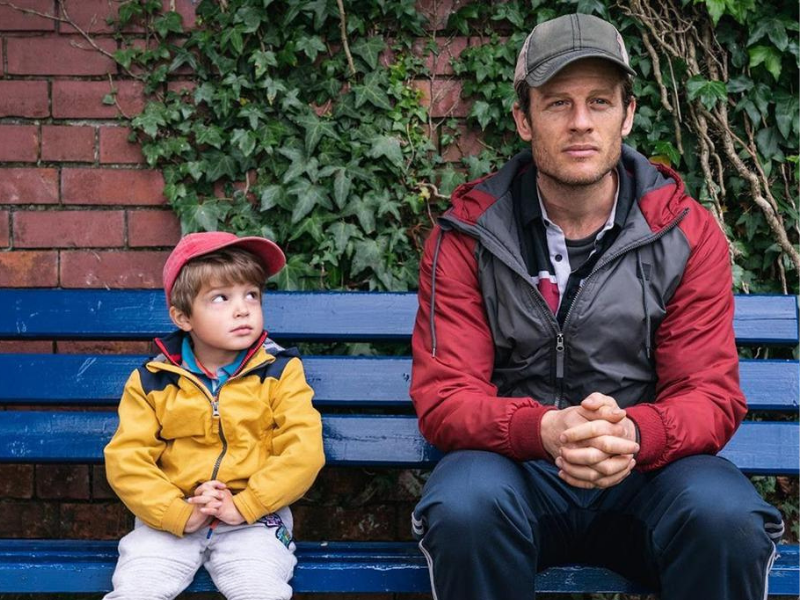
The backdrop of a constant flow of awful news, was given some temporary relief through film. “Nowhere Special” is a marvellous little film from Director Uberto Pasolini and I think it’s quite an important one. There is some wonderful acting and storytelling. Uplifting, because against this tide of awfulness, there is the ability to see a different life, to walk in the shoes of someone else. Yet it is most definitely a tale of sadness.

In a nutshell, John (James Norton) is a single parent, raising his primary-school aged son Michael. John has a terminal illness and is attempting to find a family that will adopt his son.Certainly, it’s a horrible situation, one in which I am reminded that life gets turned upside down by changes to health. The only good thing about cancer is the opportunity it usually provides to prepare for death in a way that most of us do not.

Toby, (one of my closest friends) died from cancer in 2006. That’s already fifteen years ago! He was 37. His original diagnosis was in 1996, it was rare – multiple endocrine neoplasia (MEN). We were both grateful that I’d persuaded him at just 26 to take out some financial protection which mercifully paid out once he was diagnosed. It wasn’t anything like “enough” in my view, but at the age we were at the time, neither of us really expected the array of problems that come with poor health and the impact on family finances. We simply didn’t know better. There were many difficulties and awful experiences, as well as many wonderful ones. It doesn’t seem 15 years ago.

NOWHERE SPECIAL

HOW WILL WE BE REMEMBERED?

A topic of conversation was regularly how his two children would remember him. He created a memory box for each of them, wrote journals and placed important mementos into their boxes (something that John does in the film too). To my mind it was a valuable use of his time, despite his sapping energy levels. I was reminded of this experience watching the film. Michael, (the son) is younger than either of Toby’s two children at the time, though both they and mine lived through the experience of regularly wondering when the end may arrive. Unlike Michael, Toby was married and not alone in raising his children or facing cancer. It became clear to me that whilst he had the diagnosis, cancer was a daily reality for them all.

This is not an attempt to get you to take out insurance. To be blunt, I’m more concerned that you (and I) have good relationships with those we care about and, if I may, encourage you to leave some form of memory box of who you are. I know life is a journey, that we change and evolve over time, but as Chirstmas time is upon us, take a moment to ponder how those closest to you might remember you. Perhaps a memory box should be a work in progress – a reminder of who we are and who we are becoming. Christmas is of course a time for good cheer, but its also a milestone in all our lives (however we feel or whatever we believe about it). It acts as another measure of time and the direction in which we find ourselves.

I don’t think it too bold an assumption to presume that you have had difficulties in your life, that you have known loss and grief. As a financial planner, it is a regular part of my work and over the last 3 decades I have seen and felt the impact. We plan for these awful events but experiencing them is usually rather more emotional. That’s why I urge you to get your Will done, your Power of Attorney in place and a suitable amount of protection. I hope it’s something you don’t have to experience for a very long time, but death eventually comes to us all.

Life can change very suddenly, as your planner I help you prepare for the worst whilst hoping for the best. As for today, live it as fully as you are able, make good memories.

Anyway, here is the trailer. It’s worth your ticket price and some. 9/10. I think it’s rather special. Its certainly available via Curzon and I hope other platforms too.

Get in touch to talk over any issues that this raises for you. For clarity I have had permission to from Toby’s widow to relate this story. If you know anyone with MEN, there is a very good charity (AMEND) that has much more information.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

NOWHERE SPECIAL2025-01-23T10:52:06+00:00

BROWN PAPER PACKAGES

TODAY’S BLOG

BROWN PAPER PACKAGES…

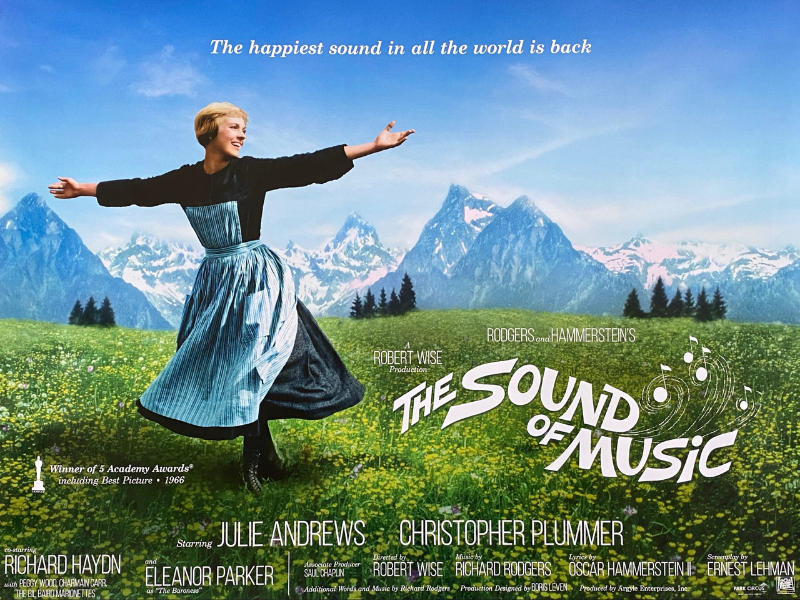
It’s that time of year when the parcels arrive in brown paper packages, tied up with strings and yes I’m sorry I cannot help but fill in “these are a few of my favourite things” such is the embedding of “The Sound of Music” in my psyche having raised a family that love musicals and Julie Andrews in particular!

I was struck by something I saw online – “Is there anything more saccharine than The Sound of Music”. Red flag, hold the phone, don’t overreact! I know musicals aren’t to everyone’s liking, and yes, it’s not Tolstoy, it is the Hollywood version of a true story, so some sugar and spice (or lack of) are part of the package. I didn’t think it was quite “fair”. This is after all, a story about the repressed being oppressed and finding a way to liberate themselves in more ways than simply crossing the alps to Switzerland, but perhaps I should try to see the other point of view.

It did get me thinking about the actual story, which is a little more real-life gritty. So perhaps a bit more background is necessary.  Firstly, Georg Von Trapp (31) married his first wife Agathe Whitehead (20) on 14 January 1911.  Agathe was the daughter of Robert Whitehead a highly successful engineer who designed the Whitehead torpedo. Her mother was part of the Austro-Hungarian nobility and the assassination of Archduke Franz Ferdinand and outbreak of war resulted in the family assets being frozen and forbidden from leaving the country. Georg was a naval officer having followed his family vocation that had resulted in elevation through the social ranks to nobility. He became an early submariner commanding the SM U-5 and was decorated for the sinking of various British, French, Italian and Greek vessels. Their first child Rupert was born in November 1911, over the next 10 years they had six further children. As we live with covid, 100 years ago scarlet fever was much more common and in Christmas 1921 five of the children suffered from scarlet fever during an epidemic, including Agathe who eventually died as a result at the age of just 31 in 1922.

The Sound of Music (1965)

HOW DO YOU SOLVE A PROBLEM LIKE MARIA?

In 1926 Von Trapp hired a novice from the local Abbey in Salzburg, Maria Kutschera. Maria’s own mother died when she was 2 and her father left her with his cousin to care for her whilst he travelled the world to manage his grief and died when she was 9. Despite a difficult childhood she completed school with good grades and eventually received a scholarship to the State Teacher’s College in Vienna from which she graduated in 1923. At age 19 she entered Nonnberg Abbey intending to become a nun.

Within a few months of her position at the von Trapp home, Georg asked her to marry him and according to Maria she returned to the Abbey to seek advice from the abbess. They married in November 2027, Georg being 25 years older unlike Julie Andrews who was just 6 years younger than Christopher Plummer (unusual for Hollywood). Maria wrote that she was really marrying the children, that she wanted to be a nun, she liked Georg but did not love him. They had their first of three children in 1929.

FINANCIAL RUIN

The Whitehead family wealth was largely held in England, but by 1935 with growing tensions in the now land-locked Austria from a hostile Germany, Georg transferred the savings into an Austrian Bank which unfortunately collapsed, resulting in the loss of most of the family fortune. The family had to discharge most of their servants and lived on the top floor of their home whilst renting rooms to others.

One tenant was a newly graduated young catholic priest, Franz Wasner who taught the children music. German soprano Lotte Lehmann heard them sing and suggested they perform paid concerts with Wasner as musical Director. Germany took over Austria in 1938 and Georg was offered a commission in the German Navy, he declined and it is also alleged that he declined an invitation for the family to sing at Hitler’s birthday. Later that year the family left Austria by train initially to Italy and headed for the US via London. They returned for a singing tour of Europe in 1939 avoiding the Third Reich but by September made their way back to the safety of the US, where they lived for the remainder of their lives. Georg died in May 1947 from lung cancer. Maria eventually died in March 1987.

On reflection, perhaps The Sound of Music is rather saccharine, by comparison to the difficulties that the von Trapp family experienced. The basic skeleton of story is there, but many of the traumatic, life shaping experiences are glossed over. What is interesting from a financial planning perspective is how quickly fortunes can alter. Within no more than two decades the Von Trapp’s had lost their wealth, their status, their home, their country. They took on a new vocation, touring as a family singing group.

CLIMB EVERY MOUNTAIN

Unlike the Von Trapp family, with good financial planning, assuming that your lifestyle doesn’t become significantly more elaborate than it is, we work together to ensure that funds survive you and that you provide a legacy for those you wish to. Whilst we can never know the future (fortunately) we can prepare for it as well as possible, doing our best.

One of the main advantages of a global stock market is the ability to diversify assets around the world, reducing risk of permanent loss considerably. Your portfolio now has between 16,000 and 30,000 securities – that’s an enormous amount of diversification around the world.

Anyway, as the year draws to a close, perhaps Julie Andrews will be on screen again. Wherever you are this Christmastime I do hope that you receive some packages, some perhaps in brown paper tied up with string.

So long, farewell…

The Sound of Music (1965) Directed by Robert Wise

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

BROWN PAPER PACKAGES2025-01-28T10:05:57+00:00

STATUS AND HEALTH

TODAY’S BLOG

STATUS AND HEALTH

I’m sure I’m not alone when I say that I have always underestimated how important it is to listen to your body. Your body is there to protect and serve you. Cues for hunger, tiredness, pain etc … are all important messages that your body needs you to pay attention to (your body is after all just doing its job).

Unfortunately, more often than not, we lead busy lives where something else or someone else’s needs come first and unfortunately in my case, this pattern of behaviour of ignoring pain and tiredness has led to me to becoming quite unwell.

We live in a society where our status is very much dependent on how busy we are (or are perceived to be). We are often ‘rewarded’ for putting our bodies second to our jobs, to our social lives, to our families … but persistently neglecting our own health ultimately impacts our jobs, social lives and our families, so it is in fact an important truth that we must look after ourselves first (in much the same way as in an emergency on board an airplane, parents are encouraged to put on their own mask before helping their children with theirs).

At the moment, I am trying to find the right balance of work, physical activity, rest and food that my body can tolerate, but maybe if I had paid more attention to what my body needed sooner, then maybe I wouldn’t be in quite the position I am now.

There is a clear analogy to be drawn here with financial planning in general and with the services we provide at Solomon’s in particular.

Your financial health and well-being is important and needs to have attention given to it … you cannot ignore the ‘niggles’ otherwise they become chronic.  In much the same way as compounding interest creates huge gains over time; compounding your ‘problem areas’ creates the opposite effect – amplified and worsened by virtue of being neglected (or fed!).

Encouraging introspection in the world of financial ‘stuff’ can often be uncomfortable (and sometimes downright painful); but just like good physio, there is a huge benefit to be had in the process.

Improving ‘financial behaviour’ is one of the most challenging elements of the work that we do for our clients … we often find that propensity for certain behaviour traits is ingrained and can take many years to overcome … that is why we are ‘in it for the long haul’ with you … we will encourage and support whenever we need to and as some of our clients will attest, Dominic can be ‘firm and assertive’ when called for to ensure that a client doesn’t make a costly financial mistake!

We are not just about ‘the numbers’ here – your financial wellbeing is our concern … it needs to be looked after and monitored; reviewed and adjusted as time goes by since the ‘niggles’ change over time.

Abigail Liddicott and Debbie Harris
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084
7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

STATUS AND HEALTH2023-12-01T12:13:00+00:00

KINTSUGI

TODAY’S BLOG

KINTSUGI

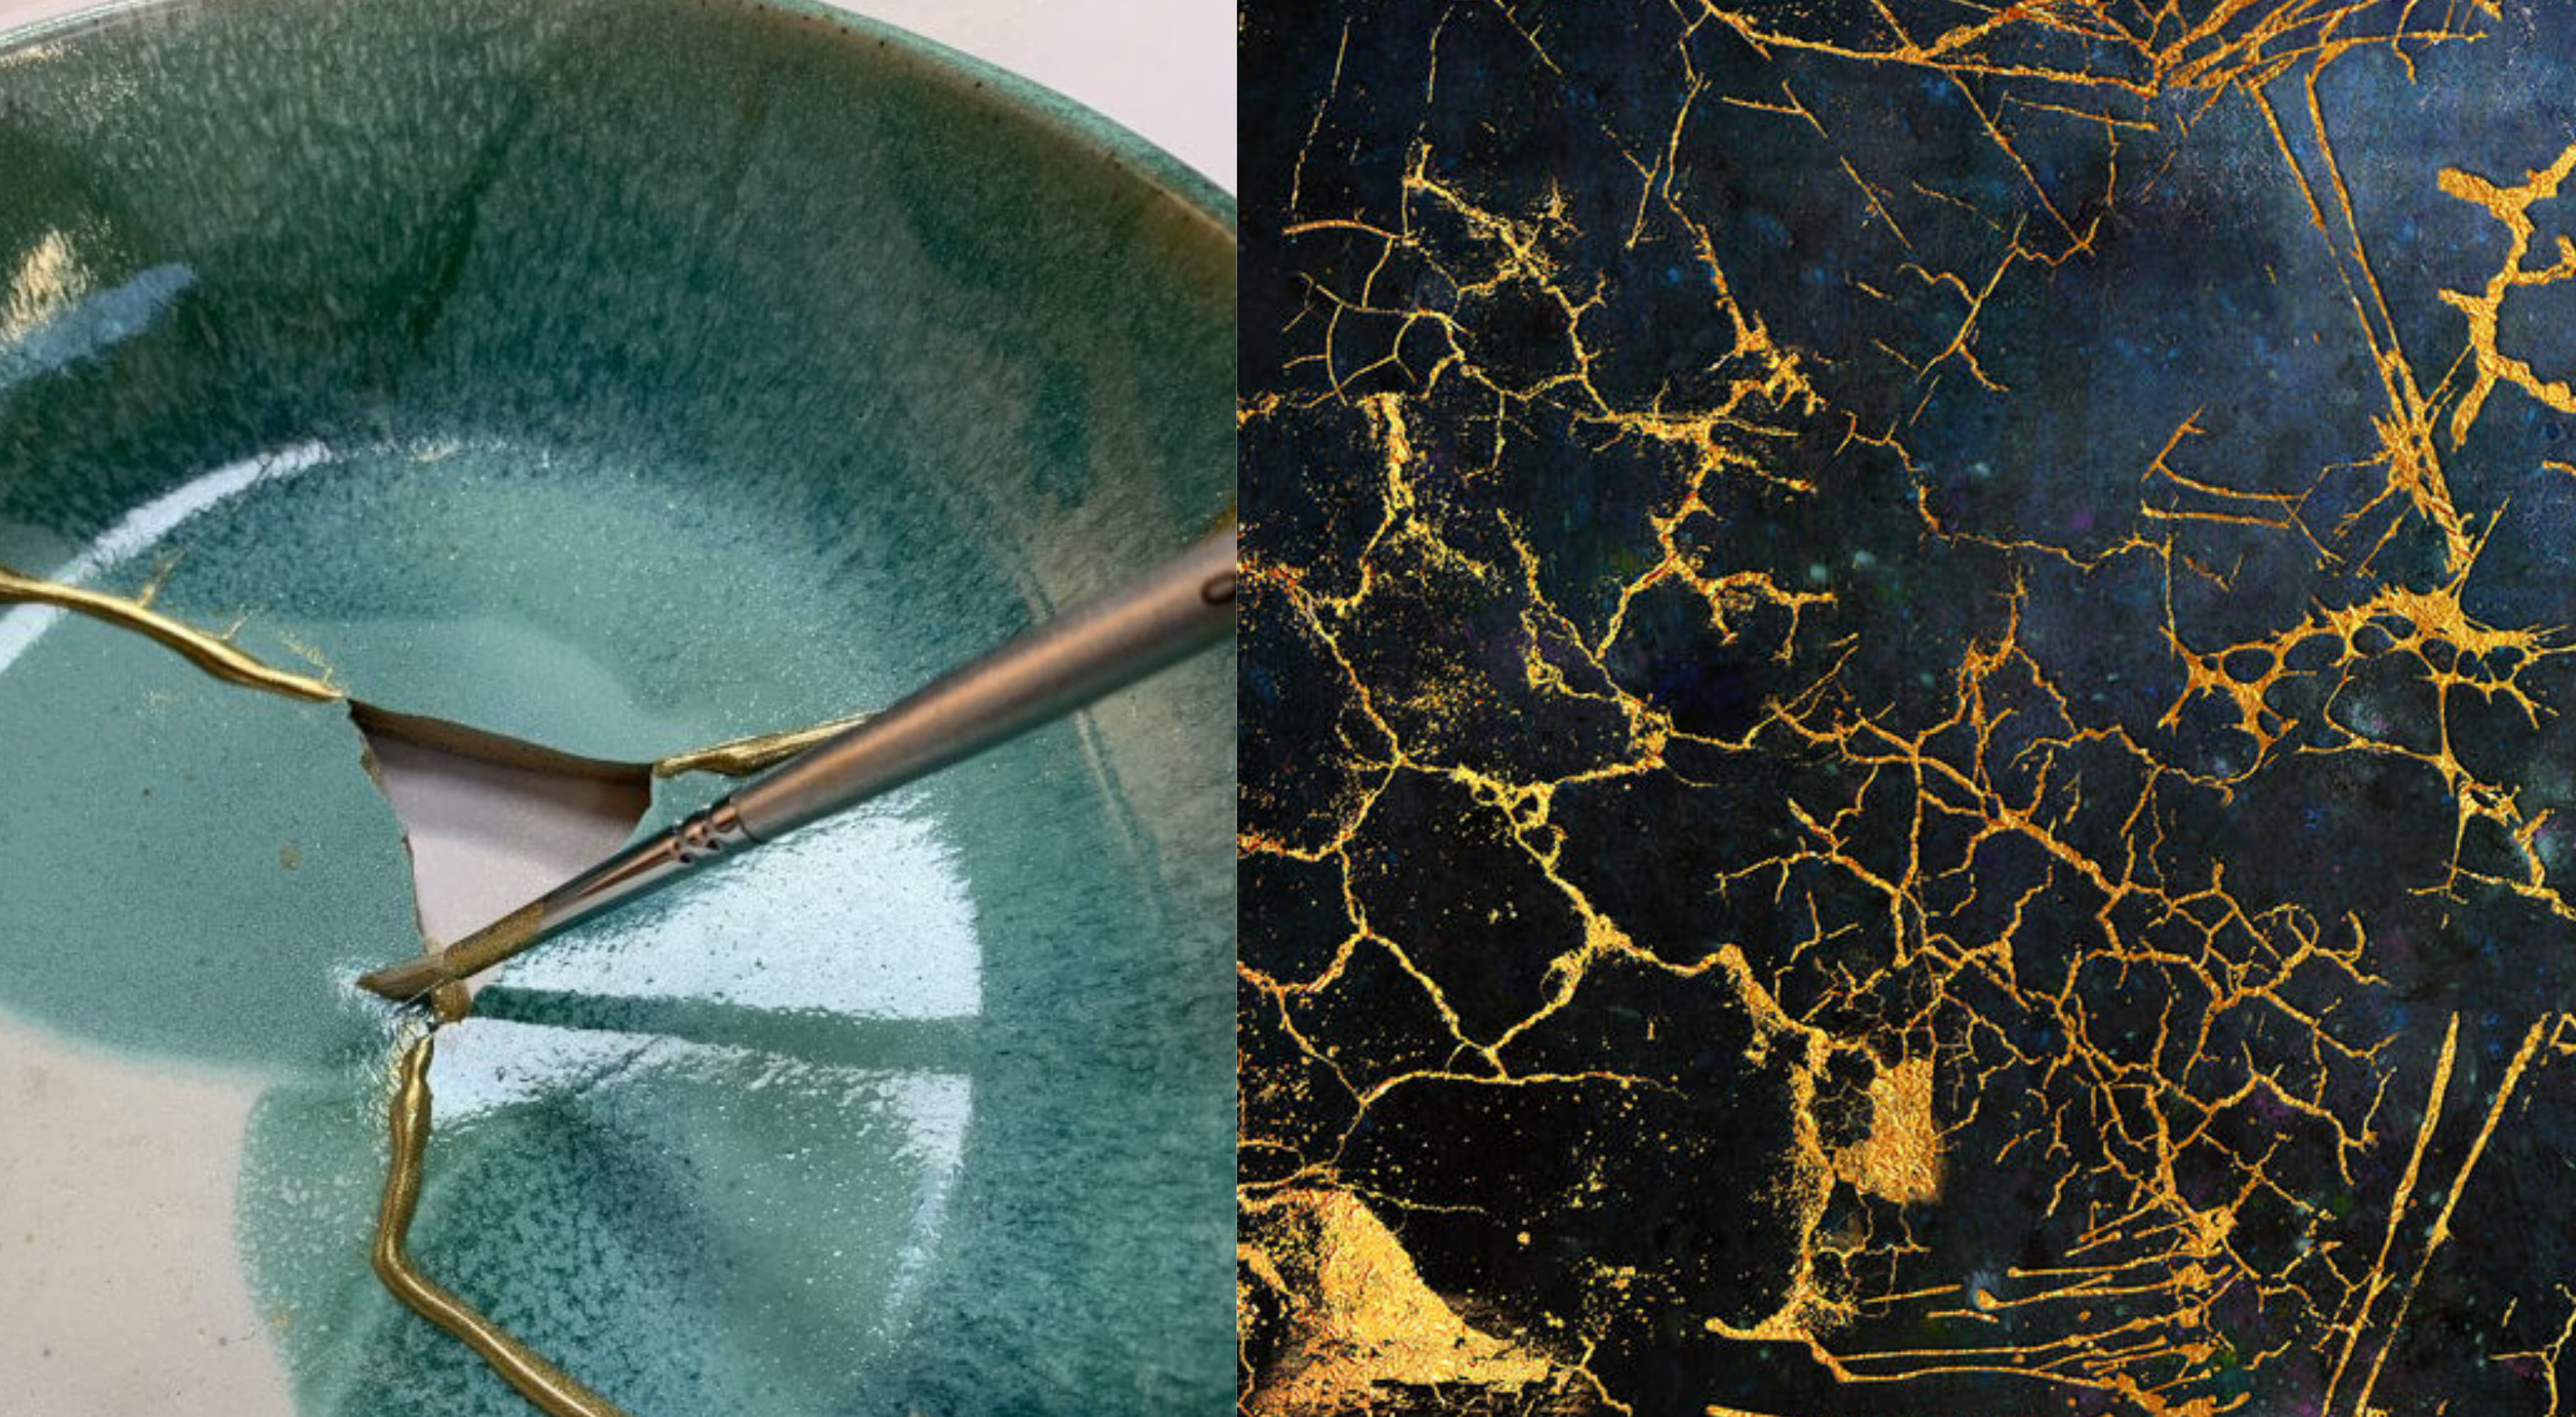
I first spotted a reference to this 400 year old Japanese art form whilst I was watching the delayed 2020 Olympics in the Summer (I can’t believe I had never heard of it before) … the BBC did a really nice VT about it and it really resonated with me.

I recently had a conversation with a close friend who had experienced a very traumatic bereavement and she said that she still felt like she was a ‘mosaic’ in her grief … a broken tile that she was haphazardly putting back together – we talked about Kintsugi (Japanese for ‘golden repair’) and it was a light bulb moment for her … that there was a sense of beauty in the rebuilding of her fractured life.

WHAT DOESN’T KILL YOU MAKES YOU STRONGER

The old adage “what doesn’t kill you makes you stronger” holds good in the depths of our humanness; but Kintsugi is a stunning physical representation of this.

From a very practical viewpoint, I can’t abide ‘waste’ of any description – time, money, resources etc; so Kintsugi appeals to me on a very basic level!  If only I could afford to buy a piece of this art for myself!  Maybe I’ll have to add it to my bucket list of ‘new skills to learn when I have the time’ (note – I am not creative at all, but I do like to fix things so maybe this is the perfect hobby for me?)

We generally try and find a way to relate our blog posts to financial planning and sometimes it’s difficult to find a parallel; but this one is easy … when new clients come to us they often have a random and disorderly selection of ‘pieces’ that we help them to put together into something meaningful … and there is great pleasure to be had for us and them when the final ‘piece’ is ready – I’m not sure financial planning is quite what you would call an ‘art form’ but there is here too an unexpected beauty in the process …

Debbie Harris
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on our blog which gets updated every week. If you would like to talk to us about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

KINTSUGI2023-12-01T12:13:01+00:00

ENERGY COST CRISIS

TODAY’S BLOG

ENERGY COST CRISIS

It seems that there is a weekly crisis at present, by the time you read this there will likely be a new one! I wonder if you are bracing yourself for an expensive winter? As you probably know, there is a global surge in the cost of gas at wholesale has led many companies to drastically increase their prices. While many companies have reacted by hiking up costs even more for customers, others have taken themselves off price comparison websites and some have gone bust. Its worth mentioning that price comparison websites aren’t all that you may imagine, they are not whole of market and only show companies that provide them with a commission.

Anyway your household and mine are facing much higher gas bills this winter due to a global surge in wholesale gas prices that have forced some energy companies to go bust. The British public has already been hit with energy price hikes over the last few months and could be paying hundreds more this winter, unless they counterbalance the extra costs by making some simple changes to their usage. The news that another five energy firms have folded in recent months will no doubt worry many householders but Ofgem has said it “has systems in place to look after consumers”. An Ofgem spokesman said that currently wholesale gas prices are at a record high, driven by international supply and demand factors. This is undoubtedly putting pressure on companies – with four leaving the market over the last few weeks. In the past few months Utility Point, People’s Energy, PfP Energy, MoneyPlus Energy and Hub Energy have all ceased trading – something which is thought to have affected half a million British households.  More recently Green and AVRO Energy both collapsed with an estimated 800,000 customers between them – Octopus has stepped in to takeover.

Energy Crisis 2021

FULL OF GAS

These consumers will be given a new supplier, that means extra hassle for them with the costs passed onto customers. Speaking from personal experience, my supplier “Green Energy Network” went bust last year and we were switched over to EDF. An unfortunately timed problem with the meter itself during this period, left us in limbo as we waited for a new account to be registered and set up, which too several weeks. We finally got there and it wasnt a major problem, but it wasnt “straight-forward”.

OFGEM added that it is working closely with the Government to manage the wider implications of the global gas price increase and it is not thought that this will lead to a complete halt in supply. Make of that what you will, I’m yet to be convinced that the current Government could successfuly manage a raffle.

As such there is no better time to see if you qualify for the Warm Home Discount Scheme, which could ensure some people are £140 better off. To find out, people can speak to their energy supplier, most of them are signed up to the scheme if they have 250,000 customers or more. More than two million UK households should qualify for this rebate on their energy bills this year and it’s important to get in touch with them early as there is only a limited amount of people energy companies can help.

What I might suggest is that you get on with reviewing your gas supply. I would recommend having a look at Martin Lewis’ website www.moneysavingexpert.com where you can do a search. If you want a £50 discount off Octopus, here is a code that you can use (I get £50 too) but do your own research about what is best for your usage. Here is the link: https://share.octopus.energy/tulip-shark-521.

Long story short, make a record and update your spending plan – either just let us know with an email, or update your information within our secure portal.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

ENERGY COST CRISIS2025-01-27T15:37:51+00:00

CASH IN HAND?

TODAY’S BLOG

CASH IN HAND?

At this stage, I am hopeful that the pandemic is drawing to a close, but aware that there are still potential problems and concerning infection rates. As many of us have been tucked away out of harm’s way, you may have had little use for your cash, making most of your purchases online or using contactless payments.

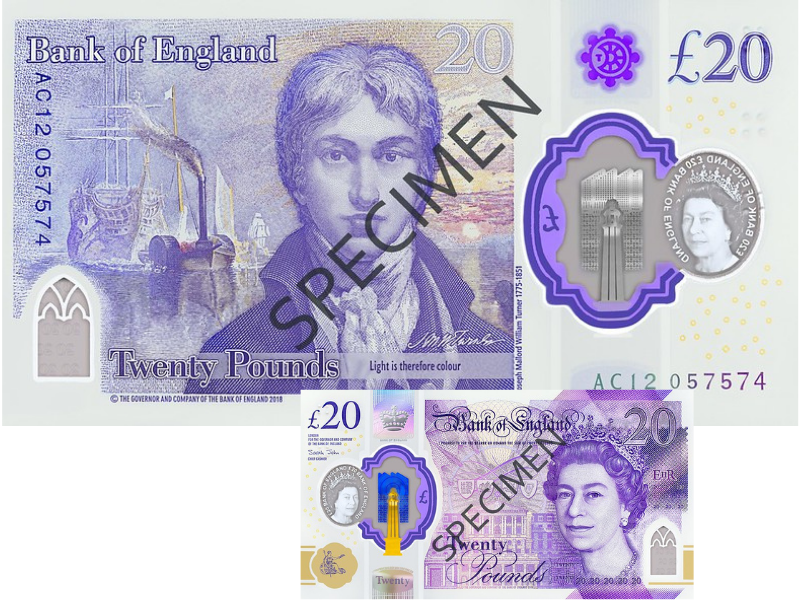
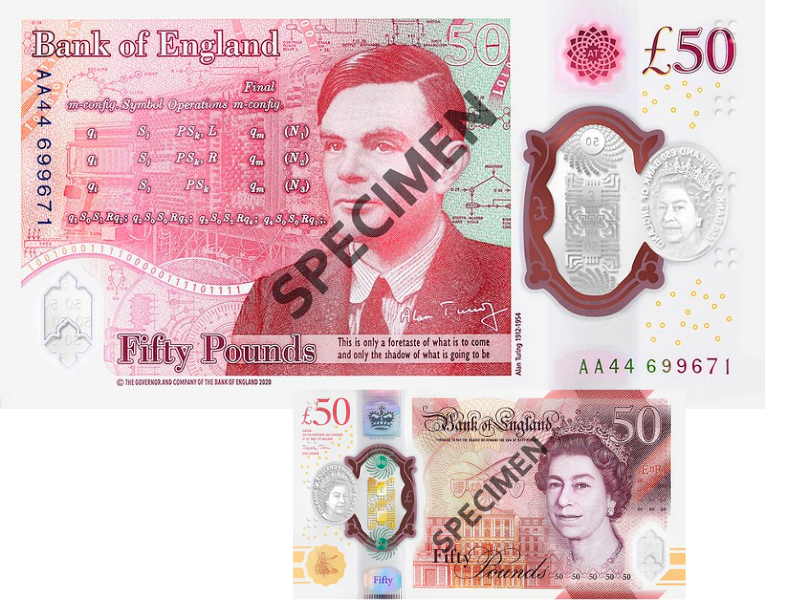
As we all gradually find our winter coats, perhaps there is a crumpled £20 note in a pocket, or better still £50. Well, take this winter as your last reminder that the old £20 and £50 notes are due to be “worthless” from 30 September… next year!

You really have the usual options of spending or depositing them, but leaving the old £20 or £50 in a wallet will soon be an expensive receipt.

New Polymer £20
New Polymer £50

MONEY GOES AROUND

There are approximately £9 billion worth of paper £20 and £15 billion worth of paper £50 notes still in circulation. As they are returned to the Bank of England, these are being replaced with the new polymer £20 notes featuring J.M.W. Turner, and polymer £50 notes featuring Alan Turing. After 30 September 2022, the new polymer notes will be the only ones with legal tender status.

After 30 September 2022 people with a UK bank account will still be able to deposit withdrawn notes into their account. Some Post Offices may also accept withdrawn notes as payment for goods and services or as a deposit to an account accessed via them.

The Bank of England will continue to exchange all withdrawn notes. For more information on this please see their Exchanging Old Banknotes page.

Speaking ahead of the date, the Bank of England’s Chief Cashier Sarah John said “In recent years we have been changing our banknotes from paper to polymer because this makes them more difficult to counterfeit, and means they are more durable. The polymer £20 featuring the artist J.M.W. Turner, and the polymer £50 featuring the scientist Alan Turing are now in wide circulation, and we are in the process of withdrawing their paper equivalents. So we want to remind the public that they have one year from today to spend their paper banknotes.”

The new polymer £20 was first issued on 20 February 2020, and the polymer £50 note was first issued on 23 June 2021. You may not have even seen one yet! These notes complete the Bank of England’s first polymer series. The introduction of polymer banknotes allows for a new generation of security features which make them even harder to counterfeit. The notes are also resistant to dirt and moisture and so remain in better condition for longer. These notes also have tactile features that allow the blind and partially sighted to use them.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

CASH IN HAND?2023-12-01T12:13:03+00:00

THE CHERRY TREE

TODAY’S BLOG

THE CHERRY TREE

I think it is a Chinese proverb that ask:

When is the best time to plant a cherry tree? Ten Years ago.

When is the second best time to plant a cherry tree? Now

I love proverbs (and old adages … and frankly the odd cliché or two!), but I have often struggled with this particular one.

In my spectacularly naive early twenties, I supposed the proverb to be all about starting young and getting on with it; having goals and taking steps to achieve my objectives and ambitions.  And throughout my twenties I worked incredibly hard at ‘living this truth’.

Following the arrival of my son in my mid-twenties, my career nose-dived; before my beautiful boy was even six months old, I was made redundant. Self-employment followed before taking on a job I loathed (but stuck at for 12 months before acknowledging defeat) and finally ending in a short period of unemployment.

I learned some pretty tough lessons the hard way during those years.  I also learned some pretty awesome things about myself too – that I was up for the challenge; that I was resilient; that I was resourceful – and most importantly that I could reinvent myself and simply start over.

I could plant a cherry tree…

Proverbs to live by

CONSCIOUS THOUGHTFULNESS

It wasn’t so much about the fact that I would have to wait 10 years to taste its fruit; it was that I had actively and consciously with thoughtfulness and determination, set in motion a chain of events that I would relish, savour and enjoy over the coming years (it’s about the journey as much as the destination – well … I did warn you that I like a cliché!).

To me this proverb (as with most of them) means more than just one thing – it can have different meanings for different people and even different meanings for the same person over time.  The cherry tree proverb addresses procrastination, regret, hindsight, patience, a long-term mindset … but most importantly it makes a clear declaration that it is never too late to start!

NEVER TOO LATE

We had the honour recently of welcoming some new clients to the Solomon’s community who were well into their retirement, but recognised that they wanted to plant their cherry tree and it didn’t matter that they may or may not be around to see it bear fruit – just knowing that it will is enough.

We would always encourage people to get financial planning as ‘early’ as possible – so long as ‘leaving it late’ doesn’t become ‘leaving it’.  I will leave you with a final thought – financial planning is not the cherry tree itself – financial planning is the soil …

Debbie Harris
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

THE CHERRY TREE2023-12-01T12:13:04+00:00

AS SAFE AS HOUSES…

TODAY’S BLOG

AS SAFE AS HOUSES

I am not really sure what the reason is, but most people trust their own bank. I guess that a degree of trust has to be there in order for you to agree to bank with them. However, there is a huge amount of inertia when it comes to banking. I don’t know if it is still the case but not so long ago a bank customer was more likely to leave their marriage than the leave the bank.

On 8 July 2021 the regulator concluded yet another investigation and disciplinary action against the Bank with the horse (again). This is prone to jokes about stable doors and a few about the long face. This time house insurance sales. Those awkward hassle reminder letters that tell you its time to renew.

I’m stretching a little, but I am basing my own assumptions on the statements made by the FCA. Long story short, loyal customers were not getting deals they thought were good and there was never any real attempt to compare just how wonderful the cost of insurance was against others. This all happened a few years ago… back in 2017 the home insurance market of 18 million policies and 12.29% of those with Lloyds Bank General Insurance. I make that about 2.2m policies. The premiums paid to Lloyds amounted to a tidy £713m… so that’s an average premium of about £336.

LONG FACE ABOUT FINE

BOLTING THE STABLE DOOR

In fairness to Lloyds they have already repaid customers £13.5m. The FCA have fined Lloyds £90,688,400 due to the misleading renewal and marketing literature, of which there were over 9m “renewal communications” between January 2009 and November 2017. So the problem went on for 8 years and its nearly 5 years after period concerned that a fine has been issued. There really is something about stables, horses and bolting here isn’t there?

Is it just me or is this about 2.2m polices sold each year since 2009… 12 years of premiums or about £8,556m for a £90m fine. It’s about 1% of premiums over those 12 years. Fair enough I am extrapolating the data, but I doubt its far off.

May I make a suggestion? Do not use your Bank for your insurance, or indeed anything other than banking. We see this sort of stuff on a regular basis, yet people remain loyal to their Banks. Use an insurance broker who will assess the market. I use Richard Hiscox at 1Stop. The main advantage is that price competition is part of the issue, the other is whether claims themselves ever get paid out easily with minimal fuss. This experience is something most of us have little of (thankfully) but an insurance broker sees this stuff every single week.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

AS SAFE AS HOUSES…2023-12-01T12:13:05+00:00
Go to Top