The Autumn Statement 2016

The Autumn Statement 2016

With a few hours to go Philip Hammond will be delivering his first Autumn statement, perhaps his last too if reports are to be believed that he will scrap them… who knows. In any event here is my quick wish list for the Autumn Statement

My Autumn Statement Wish List

(from a financial services perspective)

Abolish the Lifetime Allowance, which is currently £1m – if you hold more than this in pensions and you haven’t already “protected it” you will suffer an excess charge. Utterly pointless and discourages people from saving for their financial independence. This would also imply scrapping all previous protections.

Abolish Taper Relief – the new rule that has caused a raft of problems for those earning over £150,000 who can end up able to pay less into a pension (and still may suffer a penalty) than can be invested into an ISA. Utter lunacy, creating enormous headache for some.

Abolish Higher Rate Tax Relief – not what you might expect me to say and on the caveat that the two previous points are met. This saves the UK considerable sums, yet continues to offer an incentive to save for a pension.
Abolish Tapered Personal Allowance – either everyone gets one or nobody gets one. At the moment if you earn over £100,000 your personal allowance reduces by 50p for every £1 over £100,000.

Scrap the new Main Residence IHT allowance – just give everyone an allowance of £500,000 and have done with it. What former Chancellor George Osborne created is a shambles of smoke and mirrors.

Re-establish the different systems for Final Salary (Defined Benefits) pension schemes without any annual allowance, restricting total contributions to any pension to a fixed % of income by the employee (it used to be 15%). Vast sums and energy is used by departments in the NHS, Teachers, Local Government etc all creating utterly pointless, time sucking reports about the Annual Allowance and Lifetime Allowance. This is completely unnecessary.

Abolish LISA – another attempt to hit pensions with the high exit charges and daft array of decisions. Scrap this and other utterly pointless versions of an ISA. Have the single ISA allowance of £20,000 invest it however you like.

Stamp Duty – introduced to calm the property market which is now largely locked up with anxiety about Brexit etc. Huge tax take by Government and feels like a mugging. This needs reduced dramatically.

Fair Taxation

Earn it and tax it here. If you or your business generate income here in the UK it should be taxed at UK Corporation tax rates. Take note Google, Starbucks and Mr Green (et al). So all that nonsense for cross transfer pricing must end.

Genuinely Seeking Transparency and Tax Simplification? Have three rates of personal tax 0%, 20%, 40%. Whatever the source (dividends, capital gains, income etc). Huge sums are wasted on preparing numbers for a system that is designed to confuse. People break the rules deliberately or without knowing.

Corporations

Businesses pay corporation tax, this could be the same rates, with different allowances as personal taxation… this might mean busineses would use their revenue to reduce profits, either through inward innovative investments, expenses, employing people or redistributing to shareholders. More innovation creates more value, wealth, jobs….more tax take.

Means-Testing

If you are retired and have an income in excess of say £100,000 you forefeit your State Pension. You also forfeit free travel on public services and also the Winter fuel allowance…. come on, if you have a £100,000 income and don’t work any more, you aren’t going to need it or miss it and a relatively small number of retired people have £100,000 pension.. but really if you are a celeb you can give up your State pension and bus pass.

Landlords

Being a landlord is just like being a business. You have power over where people live. Some vetting is clearly needed (obviously not all landlords are bad). Landlords should have to apply to be a landlord license and register properties and all those living in them. Property has to be inspected every 3 years to ensure it is suitable for real people to live in. The new rules introduced about CGT, Stamp Duty and interest relief need reviewing, fair rents and fair offsets.

Ok, highly unlikely these will happen, but I really think some better ideas from Chancellors are required…

Our APP will be updated by the end of the day with all the relevant changes. It is FREE to have simply search for Solomons Financial Planning on either APP platform. There are loads of free tools and calculators to try out including an expenses tracker.


Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
The Autumn Statement 20162025-01-21T16:34:24+00:00

Panama Papers

Panama Papers

I imagine that you will have picked up on the current big story – the Panama Papers. I imagine that this will rumble on for some time. There are lots of issues to discuss, the ability for the very wealthy to hide their wealth, those that facilitate this to happen, laws about secrecy, laws about laws, political corruption, money laundering, what is ethical, the difference between tax avoidance and tax evasion… not to mention data security.

I don’t know if my thoughts will add much to the discussion, suffice to say that “the system” (by which I mean global tax system) is so complicated that it is little wonder that it is exploited, or some may say “used to advantage”.

It is a sad state of affairs when the wealthy believe that they require such secrecy and the better questions will ask why it is really required. As for the tax system – nobody really likes paying tax, but of course if we want any sort of welfare state or viable social system, we need to combine resources collectively. I don’t know if the debate can be reduced to a matter of “vast wasted taxes spent by bureaucrats” or perhaps “we pay too much tax”.

The other Black List

Fairness is very difficult to define. The vast majority of people in the UK pay very little in direct taxes. The reality is that we are all, quite obviously, interconnected. Billionaires paying less tax than their staff simply does not seem fair in any form. I’m reminded of a line from “The Black List” in which the main character, Raymond Reddington, says “if I paid any tax I’d be furious at how it is wasted” or words to that effect.

Tax is one of those deeply divisive issues and of course is enmeshed with political ideology. Part of my job is to help clients minimise tax payments and use tax allowances properly. So I’m acutely aware that I’m part of the problem… essentially taking tax receipts off the table, so that more needs to be found. Nobody likes to see public money wasted, which merely compounds feelings of frustration. The Panama papers imply that those in charge of deciding how public finances are spent, don’t like the way they do it for their own nations.

Daring to think simply?

Does life have to be so complicated? If there was one rate of tax, would there be any need to hide money? (currently taxed at very different rates). If the very rich could declare their wealth properly, would more tax be collected? Is anyone immune from financial corruption as the numbers get larger and larger? Does the reality that the Offshore market exists confirm the suggestion that the very rich would leave, if tax rates are increased? Or have they effectively already left? Is it possible to have fair taxes when certain countries exist purely to defy such reasoning (Monaco). Certainly rather more is to be revealed by the #PanamaPapers and one thing that is certain to me…. this is not new news.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Panama Papers2025-01-21T16:34:25+00:00

Now we’re talking money

Now we’re talking money

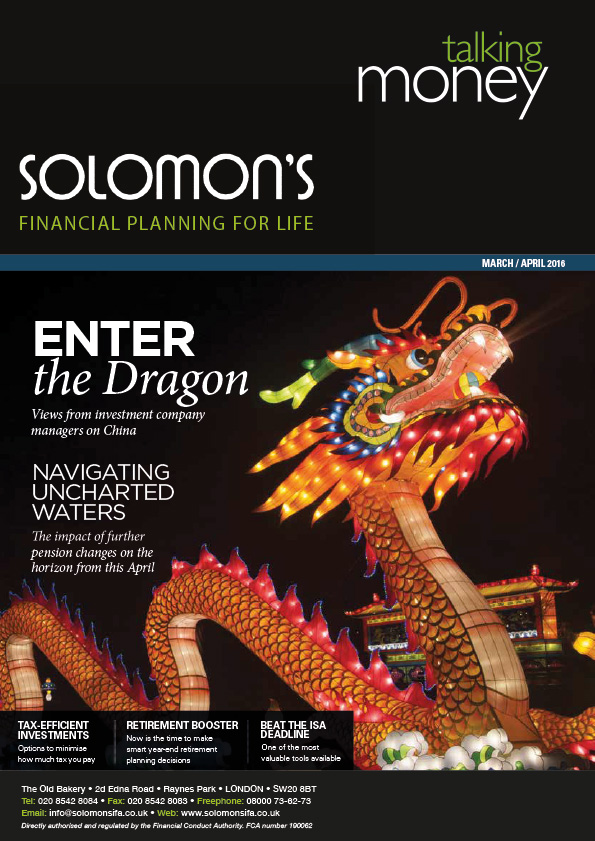
Clients will shortly be receiving a hard copy of Talking Money. In it we highlight the inevitable end of tax year issues that need consideration – or at least some of them. We also have a feature on China “Enter the Dragon” in which five fund managers provide some thoughts about the state of the Chinese market each has a point to make.

We also outline a few of the changes to the State Pension – where for once the highly complex is actually becoming more simplified, this is truly a rarity when it comes to pensions. There is also a very small note in the news section which points to some of the problems of not using an adviser.

The real cost of not taking advice

In January the FCA produced some market data in an attempt to understand the impact of the new pension freedoms (introduced from April 2015). The figures show that one in five people who encashed a pension pot of £250,000 or more took no advice.

This is alarming because they would have automatically paid tax of 45% on the pension (as income above £150,000 is taxed at 45%). Huge sums of tax have been needlessly paid, reducing the value of a pension fund far more than the credit crunch – which at least has recovered somewhat.

Some speculate that this was and is the only real reason for allowing pension freedoms – to collect far more tax. Perhaps the Budget on 16th March will provide further insight into this position.

Similarly, only yesterday I met with someone who had not protected his Lifetime Allowance, which will result in a large tax liability.

Taking advice does have a cost, but so does not taking advice, however taking advice also has a value, not doing so does not.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Now we’re talking money2025-01-27T17:02:28+00:00

Would that it were so simple

Would that it were so simple

There’s a new film “Hail Caesar” by the Coen brothers. A line which I keep finding myself repeating is spoken by Laurence Lorenz, a character played by Ralph Fiennes. He is trying to coach a stuntman with his acting – repeating the line “would that it were so simple”. It’s a funny scene, which I won’t spoil for you, but it is a phrase that I find appropriate with great regularity.

In a matter of weekends between broadsheets, the Chancellor appears to have done a U-Turn on changes to pensions. Of course had we not had all the speculation, leaks and reactions we would have been “none the wiser” of his apparent “flexibility is a strength”.

The truth is of course that we will not know what is in the Budget on 16th March until, well… 16th March and as they say a week in politics is a long time. The Chancellor is determined to control State spending and this has created a significant amount of ire and assessment in the media – as well as around dining tables in homes throughout the country.

Reshuffling the deck?

Whatever you think of Mr Osborne, as with all Chancellors, pain is delivered as discipline, where possible made to appear as a progressive change. Most of the time, there is little more being done than a reshuffling of the cards, hoping that this time, the hand will be sufficient to take home the equivalent of the jackpot.

The truth is that running the finances for the UK is not an easy task (and I am not attempting to make excuses for him). Tax revenues are based on assumptions about the future, costs are too – but there is inevitably the odd “unforeseen event” such as a plague, war or famine… which in practice aren’t really that unforeseen, because they occur regularly.

Nobody is really going to be pleased much of the time, whatever politicians tell us, we know that they have ambitions based on a concept that 4 years is the long-term, which is, as we all know, full of flaws. Would that it were so simple.

As for Hail Caesar – it is a film for our time about a film about another time, but the eternal golden rule – he that has the gold makes the rules.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
Would that it were so simple2025-01-27T17:02:28+00:00

When in Rome

When in Rome..

I recently visited Rome for the first time. It was one of those places that I have been meaning to visit but simply had never found the time. I have always had good holidays in Italy and am happy to report that Rome more than lived up to expectations.

All roads lead to Rome

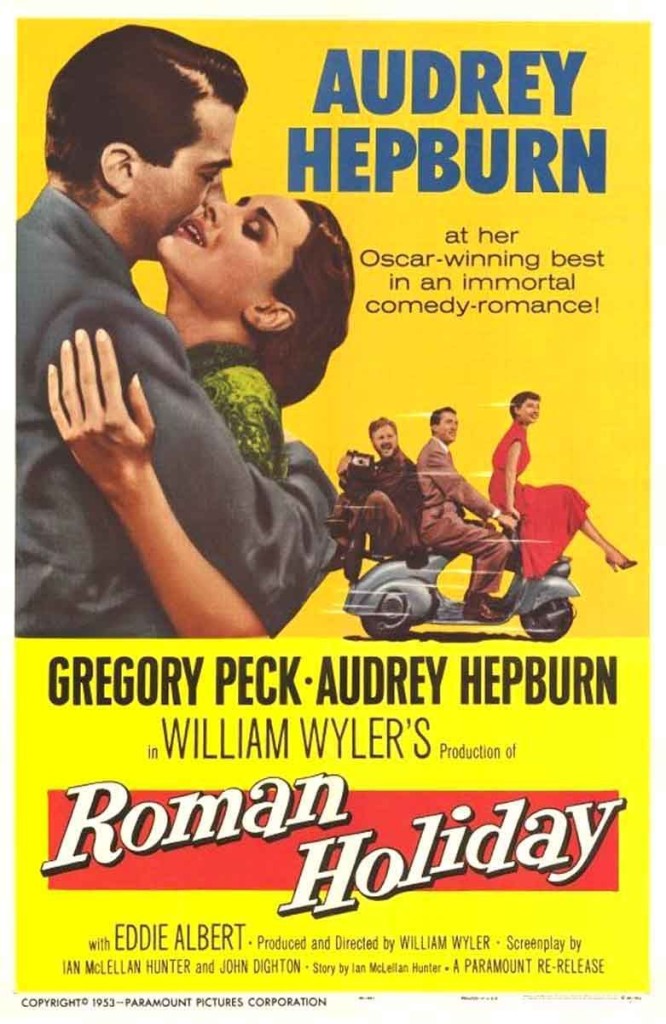
Being something of a film fan, I was keen to ensure that a few of the locations used in Roman Holiday, La Dolce Vita …were included in my visit. Having studied Latin at school (which dates me) I was also interested to see the ancient sites, many of which were part of the translation exercises that I sweated through somewhat reluctantly…. the Appian Way.

The experience of Rome reminded me of the story of the man that went to Africa and saw a huge opportunity to sell shoes, given the number of people without them. Business school suggested that this could be seen two ways – an opportunity to sell shoes or evidence that most people didn’t see the need or have the desire for them. Anecdotal observation is insufficient for making any solid business plan.

Opportunity discussion forum

Today, I might suggest opportunity of such a nature exists in Rome for driving instructors, graffiti removers and retail space designers. The driving in Rome is something to be seen to be believed. Opportunity or dead horse?

Tempus Fugit MMXVI

The Budget is now just a couple of weeks away. There is plenty of opportunity for speculation as you may have gathered. There is rumour that tax relief might be axed entirely or reduced (more likely). Supposed leaks suggest that perhaps the 25% tax-free cash lump sum will be scrapped (so some are now rushing to take theirs whilst they can). However this is in the context of the option of a pension income that is not taxed. Changes to the Lifetime Allowance, Annual Allowance and the prospect of a pension ISA.…. But by doing so, this would likely require a pre and post 2016 pension regime– just to add further complexity.

Veritas

The truth will not be known until some time after the Budget (not the Budget itself) which needs clarifying, checking and approval, is generally a promise, not a guarantee. Indeed assuming that anything that any Government says about pensions is “guaranteed” is best probably thought of only within the very short-term nature of a Government… the most obvious example being the “triple lock” guarantee for the State Pension.

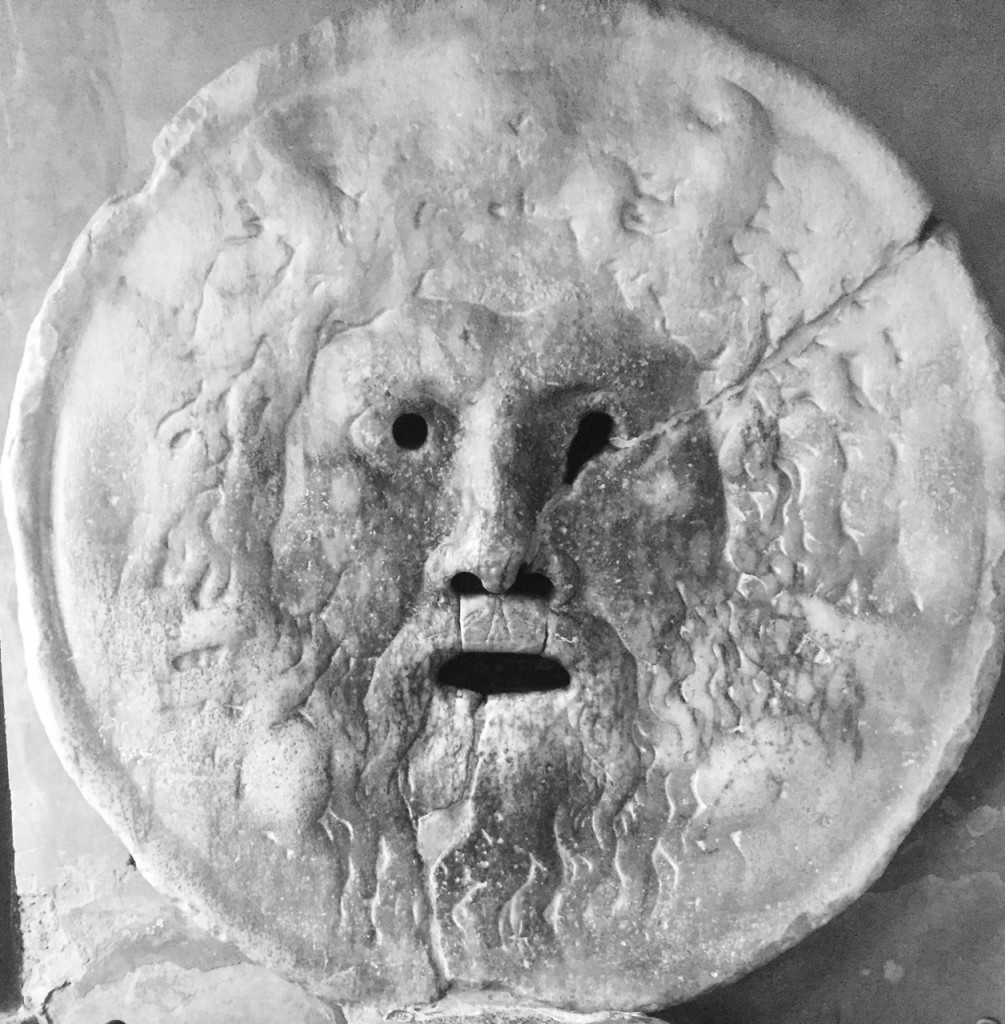
Which reminds me again of Rome, and wondering how many in our political system or media would have survived the mouth of truth…. When it comes to pensions it would appear that many will simply be flung to the lions.

MouthofTruth

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
When in Rome2025-01-27T17:02:28+00:00

The 2016 Budget, rumour has it…

The 2016 Budget, rumour has it…

As you may have gathered, the 2016 Budget is to take place on 16th March 2016. As ever there is ample speculation about what it may contain. This Chancellor has generally managed to outfox the financial services industry with changes that were not expected.

That in mind, the current rumours are that the rate of tax relief applied to pension contributions is likely to be reduced. It is expected that this will hit higher rate taxpayers the most, perhaps introducing a single rate of tax, the rumours being 20%, 25% or 33%.

Truth and rumour are rarely the same thing. However if you are swayed by the media who will now be gearing up into a mild frenzy, then give some consideration to making a pension payment before the Budget, as Mr Osborne has had a habit of using dates to suit his own purposes, rather than those of convenience.

So consider this not advice, but more of a tip, that should things change and they do so on the day, you may wish to get a pension payment made before 16 March if you are a 40% or 45% taxpayer. Of course this needs to be done in the context of your financial planning, but remember that you can invest into cash within your pension, which could act as a “holding bucket” until you discuss a strategy with us.

As ever, our APP (which is free – so do tell others) will be updated following any changes announced.

Rumour has it...

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]
The 2016 Budget, rumour has it…2025-01-27T17:02:29+00:00

Pension Tax Relief Changes?

Pension Tax Relief Changes?

It would appear that further changes for pensions are likely. Pension tax relief has been “under review” which I always take to mean a report into the impact of a decision has been already made. At present whatever your rate of tax you receive as relief for any pension payment that you make.

As outlined within this blog before, in practice this costs HMRC a lot of money and is essentially a gift back to anyone that appears to be deemed as “rich” which as far as I can tell from Government and Opposition policy is anyone earning something between £50,000 and £1million as anyone with an income above £1m seems to largely avoid paying any tax her in the UK.

The expectation is that relief will be 33% so that a neat little explanation of tax relief can be spun by the media – 2 for 1… that is £2 from you £1 from the Government. Personally I fail to see how this is sensible as it’s an extra 13% for most people and a reduction of only 7%-12% for higher and additional rate taxpayers. It would be more sensible to have a standard rate of 25% which then at least correlates to the 25% tax free cash lump sum. 3 for 1 is just as simple to spin.

Constant Changes to Pensions

This comes on the back of other pension reforms

  • Pension freedom – abolition of any requirement to buy an annuity, retaining your pension as an investment portfolio.
  • Reduction in the Lifetime Allowance (£1m from 6th April 2016)
  • Online application for Lifetime Allowance Protection
  • Reduction in the Annual Allowance to £40,000
  • Annual Allowance tapering for those with income of £150,000+ from 6th April 2016 reducing the annual allowance to a maximum of £10,000.
  • Auto Enrolment or Workplace pensions
  • Changes to what constitutes a “year” input years are reverting to tax years.
  • Flat rate State Pension
  • Changes to the State Pension Age
  • Legislation to give HMRC the ability to take money from your bank account

Some of these changes are welcome, some are not, and many seem to be altered each tax year, making planning for the future somewhat awkward to say the very least.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

Pension Tax Relief Changes?2025-01-27T17:02:29+00:00

Autumn Statement 2015

The Autumn Statement 2015

As ever, the Chancellor said a lot, made some unexpected changes and announced things that will happen and re-announced those that were already planned (all Chancellors seem to do this). In any event, the short story for most is that landlords are on the radar. Stamp Duty will be rising by an extra 3% for those buying a second property (or more) in addition to the changes already announced about interest relief.

In addition capital gains tax looks set to be something that is now much more closely inspected by HMRC and the payment for Capital Gains Tax on property appears to be moving to a pay at the time, rather than wait until the following January, which in some instances means bringing forwards the payment date to HMRC by potentially 22 months. The details are to be finalised.

The rumours about changes to tax relief on pensions changing were given further credibility with research into the impact of changes to the current 20%, 40% and 45% relief being finalised by March next year, so we would expect an announcement in the Budget next March. If I were a betting man (I’m not) I’d suspect that tax relief will become a single rate, of either 25% (which would be more logical – at least this has some link with the 25% tax-free cash) or 33% (you pay £2 we [Govt] pay £1).

In any event, our APP – the one you and your friends can have for free on iPad, iPhone or android platforms has been updated with changes appropriately.

Solomons Financial Planning APP

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

Autumn Statement 20152025-01-28T09:53:35+00:00

Budget 8 July 2015

Budget 8 July 2015

Following my recent email and Mr. Osborne’s announcements, I am pleased to confirm the following changes and amendments have been made to our App (which is available free of charge for iphone, ipad and Android platforms).

As the 2016/17 rates are being added after the Autumn Statement, there is only one small change to the 2015/16 rates and the change has already been made earlier this afternoon and is live in your App. The change was within the Main Capital and Other Allowances section of the tax tables and related to the change to the Annual Investment Allowance from 1st January 2016 from the previously announced limit of £25,000 to a new limit of £200,000.

On a separate note, the chancellor has, from April 2016, abolished dividend tax credits. This will fundamentally change 3 of the tax calculators so they will need to be changed when we complete our updates prior to the April 2016 budget. However for the remainder of this tax year, all calculators and tax tables remain fully accurate.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

Budget 8 July 20152025-01-21T16:34:27+00:00
Go to Top