Picking the triple lock

Daniel Liddicott 
Post written: Oct 2026  •  Published: Oct 2026
3 min read

Picking the triple lock

At the tail end of September, Andy Burnham announced his plan to adjust the current triple lock on State Pensions from April 2030. This would bring an end to the current method of calculating annual State Pension increases, which has been in place since 2010.

What is the triple lock?

The triple lock, introduced in 2010 by the Conservative–Liberal Democrat coalition government, has ensured that the basic State Pension and the full new State Pension increase each year by the highest of these three measures:

  • Inflation
  • Average earnings growth in the UK
  • 2.5%

From April 2030, the plan is to introduce an “adjusted triple lock”. The average earnings measure is largely being removed, with the revised system primarily ensuring that the State Pension rises by at least inflation or 2.5% each year. Unlike the other two measures, average earnings increases will no longer be used automatically should it be the highest in a given year. Instead, earnings will help to determine whether a further increase is needed to maintain the State Pension’s value relative to wages over time.

Why has this been announced?

The primary driver behind this change is to help fund a new National Care Service. The hope is that this will make the social care system work more like the NHS, with savings from the adjusted triple lock contributing towards the cost.

The current social care system is means-tested, with an individual’s financial circumstances assessed to determine how much they must contribute towards their care. In England, the lower capital limit is currently £14,250, although the rules vary depending on the type of care and other circumstances. It is not expected that all care costs would become completely free, though the clearest commitment expressed so far has been to provide free personal care for older people, based on need rather than ability to pay.

There is still much to be ironed out regarding exactly how this might work. Andy Burnham has stated that the intention is for the National Care Service to be fully funded, without the need for additional government borrowing.

How will this impact State Pension income?

In some years, the adjusted triple lock could result in smaller State Pension increases than under the current system. Taking the most recent State Pension increase in April 2026 as an example:

  • Average earnings growth was 4.8%.
  • Inflation (CPI) was 3.8%.

The 4.8% earnings figure was therefore used for the annual increase. The full new State Pension rose from approximately £11,973 to £12,548 a year.

Under a system based solely on inflation or 2.5%, the increase would instead have been 3.8%, bringing the annual amount to approximately £12,428. However, the adjusted triple lock proposed for 2030 would also include a mechanism to maintain the pension’s value relative to average earnings over time, so the long-term outcome would not be quite the same as simply removing earnings growth from the calculation.

Since the triple lock was introduced in 2010, inflation and average earnings growth have each determined several annual increases, while the 2.5% minimum has been used less frequently.

Therefore, it is quite possible that inflation will become the most commonly used measure for future increases. Much will depend on how inflation and wages evolve over the coming years. The adjusted triple lock is designed to protect State Pension income against inflation while ensuring that pensioners continue to share in wider earnings growth over time, without the pension consistently growing faster than average wages.

The precise outcomes will depend on how the new system operates in practice. The intention appears to be to balance protection of income for pensioners with the need to make the State Pension system more sustainable, and to help fund the proposed National Care Service.
Have a question or feedback about this article?

Please share this with a friend

Picking the triple lock2026-10-14T10:47:26+01:00

The State Pension – What’s Ahead

TODAY’S BLOG

THE STATE PENSION INCREASE

In early December the Department for Work & Pensions announced the proposed increases to benefits for 2021/22. Most of the working age benefits and the earnings-linked pension benefits, such as the old State Second Pension, will rise by 0.5%, in line with annual CPI inflation to September 2020. However, the new state pension and its predecessor will both increase by five times as much.

The costly Triple Lock

Both new and old (basic) state pensions benefit from the Triple Lock, which currently requires an increase which is the greater of:

  • Earnings growth;
  • Price inflation (as measured by the CPI); and
  • A floor of 2.5%.

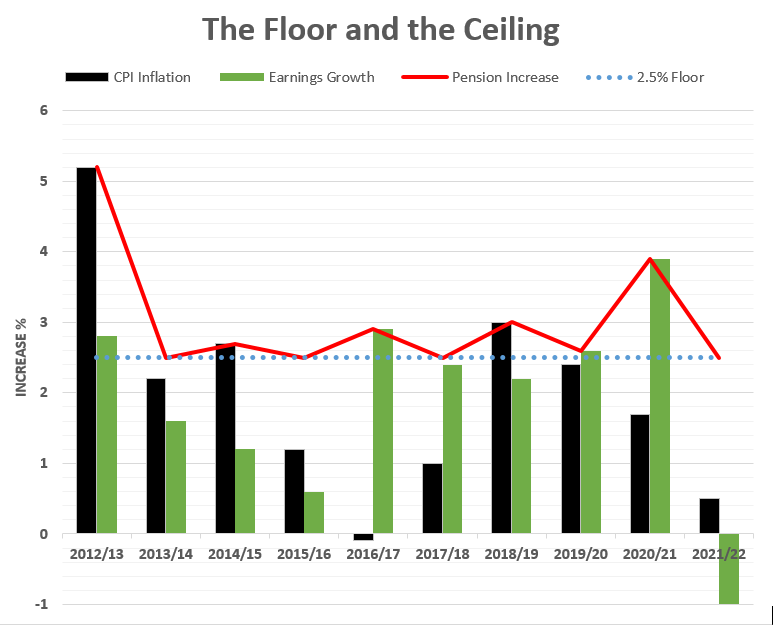
For the 2021/22 increase, the 2.5% minimum was a clear winner, with earnings growth at the bottom of the trio. As the chart shows, in this context earnings growth is a misnomer; earnings fell by 1% over the year because of the impact of the pandemic.

State Pension 2021/22 Triple Lock

10 YEARS LATER… NOT ON PLAN

Over the ten years to 2021/22, the 2.5% floor has been the basis for four increases, something which was probably not anticipated when the Triple Lock was announced by the coalition government in 2010. Then, as now, the Bank of England’s inflation target was 2.0%. Earnings were expected to outpace inflation by 1% or more, making the 2.5% floor a safety net that probably would only be called upon in a deep recession.

It has not worked out that way. Earnings and inflation have virtually matched each other over the period at just under 2%. In other words, there has been no increase in the buying power of average earnings over the past ten years. In contrast the Triple Lock has delivered a real terms increase of almost 11%. If you are on the receiving end of the Triple Lock, that is good news, but if you are under State Pension Age (66 now, don’t forget) it means more government expenditure you have to finance.

Looking ahead

The Triple Lock has been widely criticised by experts ranging from the Institute for Fiscal Studies to the Pensions Select Committee for being an unnecessarily expensive protection that creates intergenerational unfairness. In private politicians would generally agree but, at the last Election, all of the mainstream political parties committed to retaining the Triple Lock. The pensioner vote is not one to put at risk.

The pandemic may have changed that mindset. Last year the government introduced emergency technical legislation to ensure the Triple Lock would work in the face of zero earnings growth. However, the measures put in place only applied for a single year. There have been suggestions that, if no action is taken, an earnings bounce in 2021 as the economy recovers could mean a 5% 2022/23 increase under the Triple Lock formula at a time when inflation is below 2%. Given the dire position of public finances, such a scenario would offer Rishi Sunak the golden opportunity to justify a reworking of the Triple Lock.

But…  

Despite the new state pension’s outpacing of inflation and earnings growth, it will remain a distinctly modest sum in April 2021: a maximum of £179.60 a week. Viewed another way, that is equivalent to just over 20 hours’ work at the National Living Wage rate for 2021/22 (£8.91 an hour) or a little under one-third of current average earnings (£560 a week). No wonder the UK is likely to remain in bottom place of the OECD’s league table based on the proportion of earnings replaced by state pensions…

ACTION

If you want to check your projected state pension benefit, CLICK HERE TO GO TO THE STATE PENSION SITE.

The state pension is not enough for a comfortable retirement. Make sure you talk to us about how you should be supplementing it – preferably before the Budget.

Dominic Thomas
Solomons IFA

You can read more articles about Pensions, Wealth Management, Retirement, Investments, Financial Planning and Estate Planning on my blog which gets updated every week. If you would like to talk to me about your personal wealth planning and how we can make you stay wealthier for longer then please get in touch by calling 08000 736 273 or email [email protected]

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected] 
Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

GET IN TOUCH

Solomon’s Independent Financial Advisers
The Old Mill Cobham Park Road, COBHAM Surrey, KT11 3NE

Email – [email protected]    Call – 020 8542 8084

7 QUESTIONS, NO WAFFLE

Are we a good fit for you?

The State Pension – What’s Ahead2023-12-01T12:13:10+00:00
Go to Top